Options dealers sit on the other side of most customer options trades. To stay close to delta-neutral, they hedge in the underlying, and how much they hedge depends on their gamma — how fast their delta changes as price moves. When the aggregate gamma position is known, the direction and rough size of that hedging becomes a mechanical expectation: if price moves here, hedgers tend to have to do this.
Gamma Sonar estimates that dealer positioning from live greeks and open interest and turns it into levels, regimes and stress readings. None of it is a forecast. A level is where hedging behavior is more likely to change; a regime describes how hedging tends to interact with price right now. Price can and does move through all of it.
Negative net gamma — dealers tend to buy rallies and sell dips. That hedging leans with moves and can amplify volatility.
Everything else in the platform is a refinement of where those two behaviors switch, how strong they are, and how stressed the current structure is.
If these terms are new, start with the Beginner course, which builds GEX up from delta and gamma. The Advanced course covers vanna, charm and expiry roll-off, and the Expert course covers regime transitions and stress.
How the data is built
- Greeks are recomputed from the live options chain every compute cycle: every 60 seconds during regular trading hours.
- Open interest is published once a day by the exchanges (the prior session's close). Gamma Sonar combines that with live greeks, so levels move intraday as spot, time and implied volatility change — even though OI itself updates overnight.
- Universe: 150+ tickers — indexes, major ETFs and the most active single stocks. Your watchlist can hold up to 100 of them.
- Sign convention: the platform assumes customers are net long calls and net long puts against dealers. That is the industry-standard simplification. It is often right on indexes and less reliable on single names where dealers may be long calls. See Honest Limitations.
Colors mean one thing
| Color | Meaning everywhere in the platform |
|---|---|
| GREEN | Positive / supportive mechanics — positive gamma, call-side, support structure |
| RED | Negative / resistive mechanics — negative gamma, put-side, stress to the downside |
| TEAL | Current position or selected state — spot, the active tab, your current choice |
| GOLD | Warning — escape velocity, a level close to breaking |
| AMBER | Stress — Structural Stress readings and alerts |

Every page shares one shell. Learn it once and every tool reads the same way.
Topbar
| Element | What it shows |
|---|---|
| Logo | Returns to Command from anywhere. |
| Ticker box | Type any of the 150+ universe tickers to switch every tool to it. The + adds the ticker to your watchlist. |
| Spot | Last underlying price used by the compute cycle. |
| Net gamma | Total dealer gamma exposure. Green when positive (dampening), red when negative (amplifying). |
| Call wall | Strike with the largest call-side gamma — the upper edge of the positive-gamma structure. The small number beside each level is its distance from spot in points. |
| Flip | Gamma flip — where cumulative net gamma crosses zero. Above it dealers tend to dampen; below it they tend to amplify. |
| Put wall | Strike with the largest put-side gamma — the estimated lower edge of the positive-gamma support zone. A boundary, not a floor. |
| Expected move | Today's options-implied range, with its size in points and percent (see Chapter 9). |
| Regime pill | The current regime state. Open the Regime Classifier for the reasoning (see Chapter 6). |
Sidebar
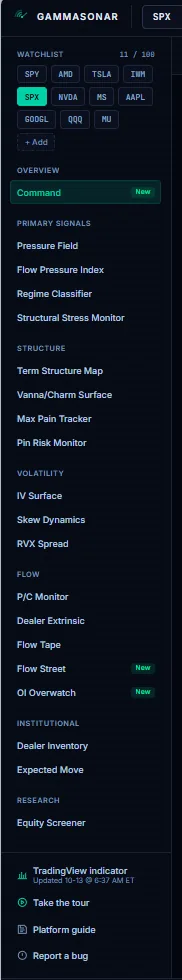
Tools are grouped by the question they answer:
| Group | Tools |
|---|---|
| Overview | Command |
| Primary signals | Pressure Field, Flow Pressure Index, Regime Classifier, Structural Stress Monitor |
| Structure | Term Structure Map, Vanna/Charm Surface, Max Pain Tracker, Pin Risk Monitor |
| Volatility | IV Surface, Skew Dynamics, RVX Spread |
| Flow | P/C Monitor, Dealer Extrinsic, Flow Tape, Flow Street NEW, OI Overwatch NEW |
| Institutional | Dealer Inventory, Expected Move |
| Research | Equity Screener |
At the top: your watchlist with its count (up to 100) — click a name to switch ticker, hover to remove, + Add to add. At the bottom, the TradingView indicator download, Take the tour, this guide, and Report a bug.
Status bar
The thin bar at the bottom tells you how fresh the data is: the age of the last GEX compute (for example "GEX 5s ago"), the market state (LIVE during the session, otherwise EOD or CLOSED), and the connection state. If the numbers ever look frozen, check here first.
Banners
Two banners can appear under the topbar. A stale-data banner shows automatically if the feed for your ticker stops updating. A site banner is posted by the Gamma Sonar team — NOTICE, HEADS UP or SERVICE ISSUE — when something affects everyone, such as a data-vendor delay.
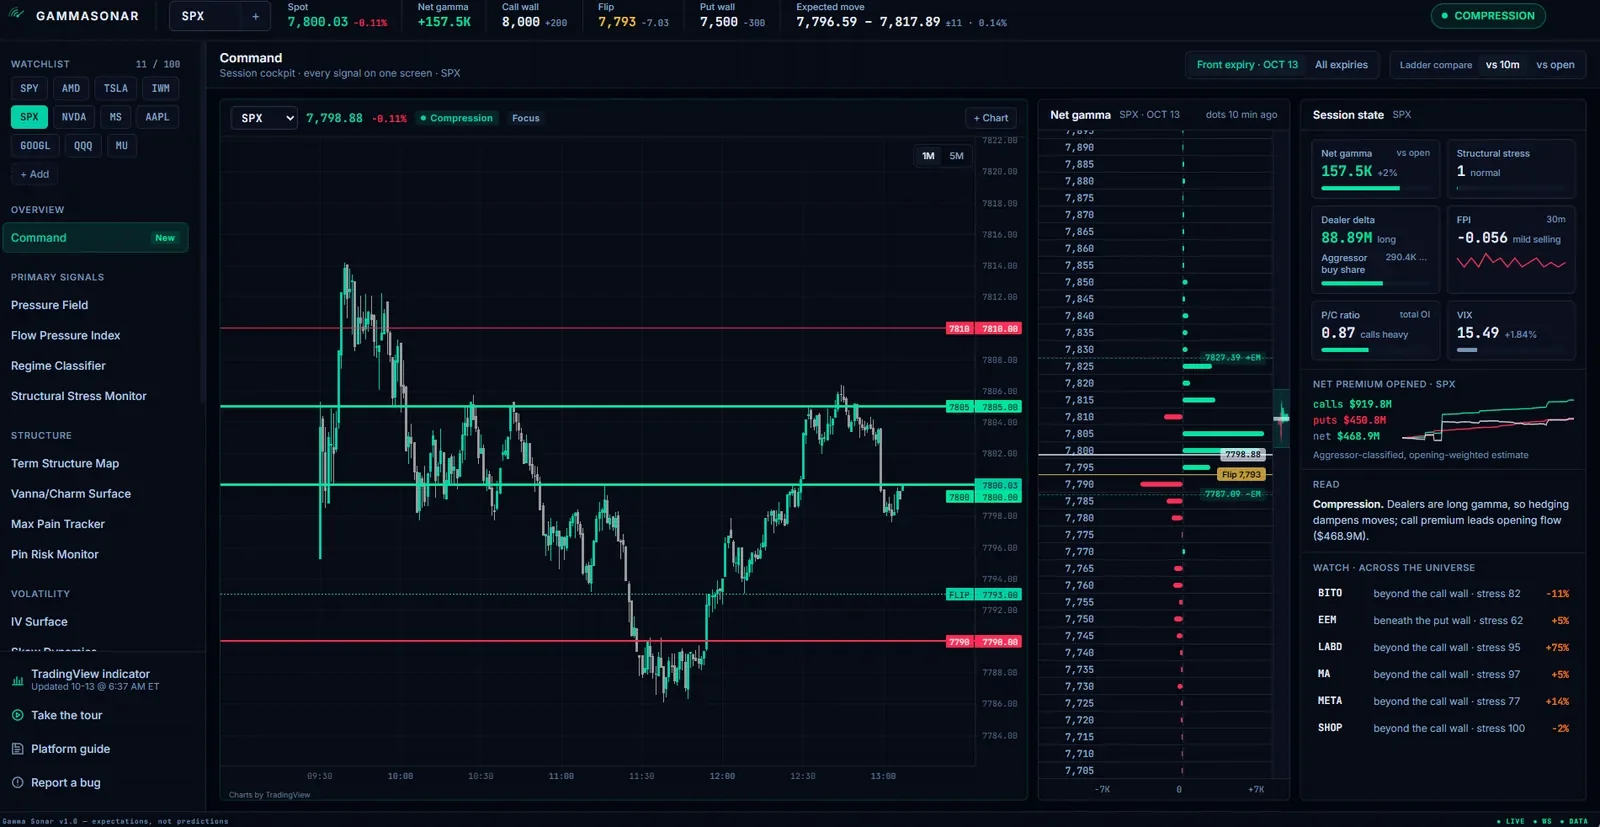
What it shows
- Price charts — one to three candle charts (1-minute or 5-minute; add more with + Chart, each with its own ticker) with the call wall, put wall and flip drawn as lines, plus the two largest gamma strikes. The chart marked Focus drives the ticker for the rest of the page.
- Net gamma ladder — net gamma by strike, with spot marked, expected-move lines, and a minimap for scrolling. Use the expiry toggle to switch between front expiry and all expiries, and the compare toggle to show change vs 10 minutes ago or vs the open (shown as dots on each row). Command opens on the front expiry.
- Session state tiles — net gamma vs open, structural stress, dealer delta (with aggressor buy share), the FPI 30-minute reading, total put/call OI ratio, and VIX.
- Net premium opened — premium flowing into new positions today, calls vs puts and net. Aggressor-classified and opening-weighted, so it is an estimate.
- Read — one plain-English sentence summarizing the current structure.
- Watch — the six names across the universe with the most notable structure right now, each with the reason (for example "beyond the call wall · stress 82") and its net gamma change vs the open.
How to read it
| Tile | Reading |
|---|---|
| Net gamma vs open | Rising: structure is getting more stable through the day. Falling toward or below zero: dampening is fading. |
| Structural stress | The SSS score (0–100). See Chapter 7 for bands. |
| Dealer delta | Estimated net dealer delta. Large values mean more hedging is needed if price moves. |
| Aggressor buy share | Share of options volume that traded at or above the ask. Above 50% leans buyer-initiated. |
| FPI 30m | Within ±0.05 is neutral. Beyond ±0.35 is strong. Positive = net buying pressure implied by hedging. |
| P/C total OI | Above 1.1 puts heavy, below 0.9 calls heavy, in between balanced. |
How to use it
Start every session here. If the Read sentence, the regime pill and the stress tile agree, the structure is coherent and the levels on the chart are the ones to respect. If they disagree — positive gamma but rising stress, for example — drill into SSS and the Pressure Field before trusting the levels.
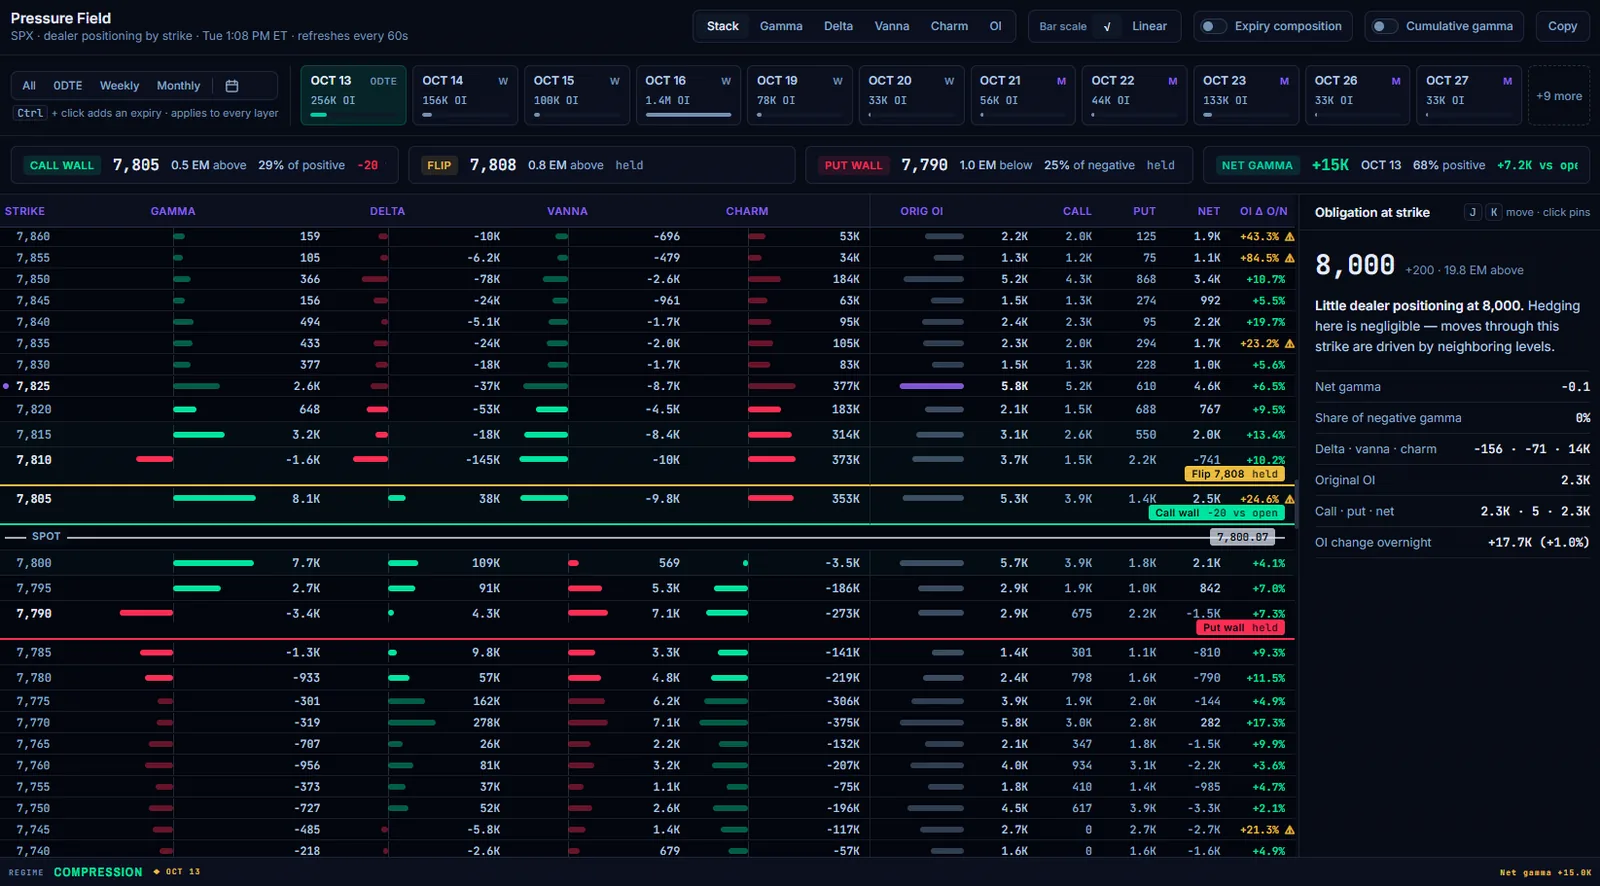
What it shows
- Layers: Stack (all greeks side by side), Gamma, Delta, Vanna, Charm and OI. Each strike is one 22px row; spot is highlighted in teal.
- Bar scale: √ (square root, the default — keeps small strikes visible) or Linear (true proportions).
- Expiry composition — how much of each strike's exposure comes from each expiry. Cumulative gamma — running total from the lowest strike up; where it crosses zero is the flip.
- Expiry rail — presets All, 0DTE, Weekly, Monthly, plus one card per expiry showing its open interest and a W (weekly) or M (monthly) tag. Ctrl-click to combine expiries, or pick dates from the calendar. The selection applies to every layer.
- Level chips — call wall, flip, put wall and net gamma. Each shows its distance from spot in expected moves, its share of positive or negative gamma, its change vs the open, and whether it has held.
- Obligation at strike (screens wider than 1280px) — hover a strike, or use J / K and click to pin one. It says in plain English whether dealers would need to buy or sell through that strike, and estimates the size to reach the next strike and per 1% move.
- Copy PNG — copies the current view to your clipboard.
Stack columns
| Column | Meaning |
|---|---|
| Strike | Strike price. Rows inside the expected-move band are tinted. |
| Gamma | Net dealer gamma exposure in dollars. Green positive, red negative. |
| Delta | Dealer delta exposure at the strike. |
| Vanna | Change in dealer delta for a change in implied volatility. |
| Charm | Change in dealer delta from the passage of time. |
| Orig OI | Open interest from the morning file. |
| Call / Put / Net | Gamma split by side and the net. |
| OI Δ o/n | Overnight change in OI. Highlighted when the change is at least 20% and at least 500 contracts. |
| Cumul. | Cumulative net gamma up to this strike. |
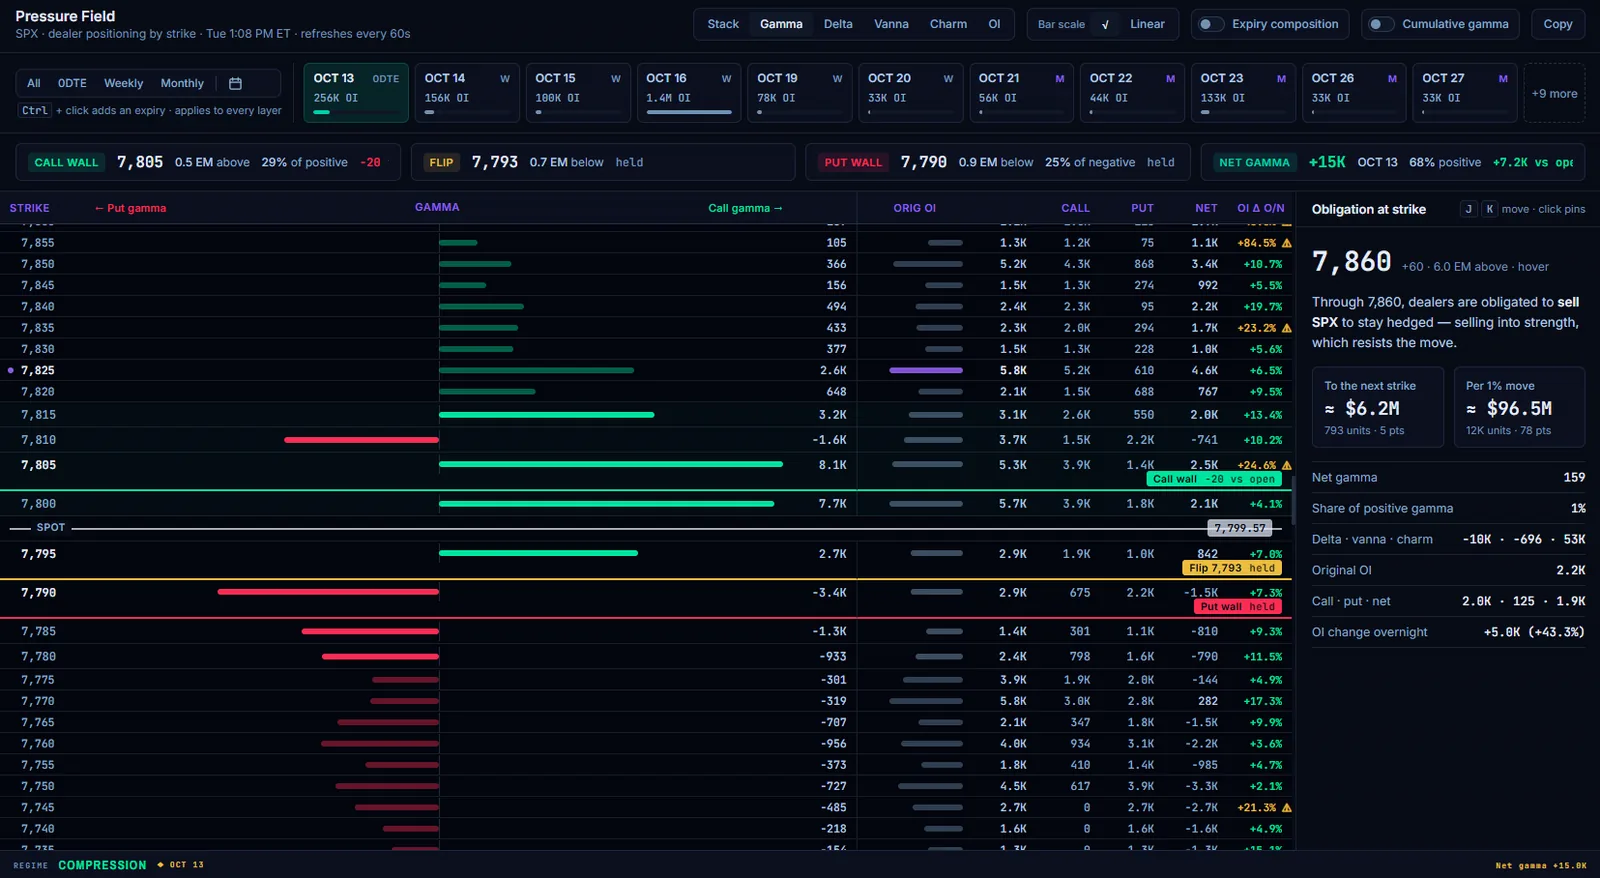
Single-greek layers such as Gamma split around a center line: put gamma to the left, call gamma to the right. The page recomputes every 60 seconds and shows the current regime in its footer.
How to read it
Large green bars above spot are structure that tends to absorb rallies; large green bars below spot tend to absorb selloffs. Red bars near spot mean hedging there tends to push in the direction of the move. The vanna and charm columns tell you how exposure will drift without price moving at all — as volatility changes and as the clock runs. The Advanced course walks through both.
How to use it
- Use 0DTE to see today's expiring structure, which dominates intraday hedging on index products.
- Use Weekly or Monthly to see what remains after today's options expire.
- Watch OI Δ o/n highlights for strikes where positioning changed meaningfully overnight.
- A single dominant green strike near spot is a pin candidate, especially late in the session on expiry day.
- When most of the gamma sits in 0DTE, levels are strong intraday but tend to vanish after the close; do not carry them overnight.
- Positive charm below spot into the afternoon tends to add dealer buying as time passes — part of the reason quiet afternoons can drift higher in positive gamma.
- Thin gamma between two large strikes is a "gap" where price tends to travel quickly.
| Level | Definition | What tends to happen there |
|---|---|---|
| Call wall | Strike with the largest call-side gamma. | Rallies into it tend to slow as dealers sell to hedge. A clean break above can signal the structure is being overrun (escape velocity). |
| Flip | Price where cumulative net gamma crosses zero. | The boundary between dampening (above) and amplifying (below). Volatility tends to change character when price crosses it. |
| Put wall | Strike with the largest put-side gamma. | The estimated lower edge of the positive-gamma support zone — a boundary, not a floor. Below it, hedging tends to accelerate declines. |
Remember which structure you are looking at: the topbar uses all expiries, while Command and the Pressure Field open on the front expiry (see Chapter 2).
Levels are recomputed every cycle. They move when spot moves (gamma depends on distance to strike), when time passes, when implied volatility changes, and every morning when new OI arrives. The TradingView indicator draws two versions of each: .F from the full chain (all expiries) and .N from the closest expiry only, so you can see both the overall structure and today's near-term structure.
What it shows
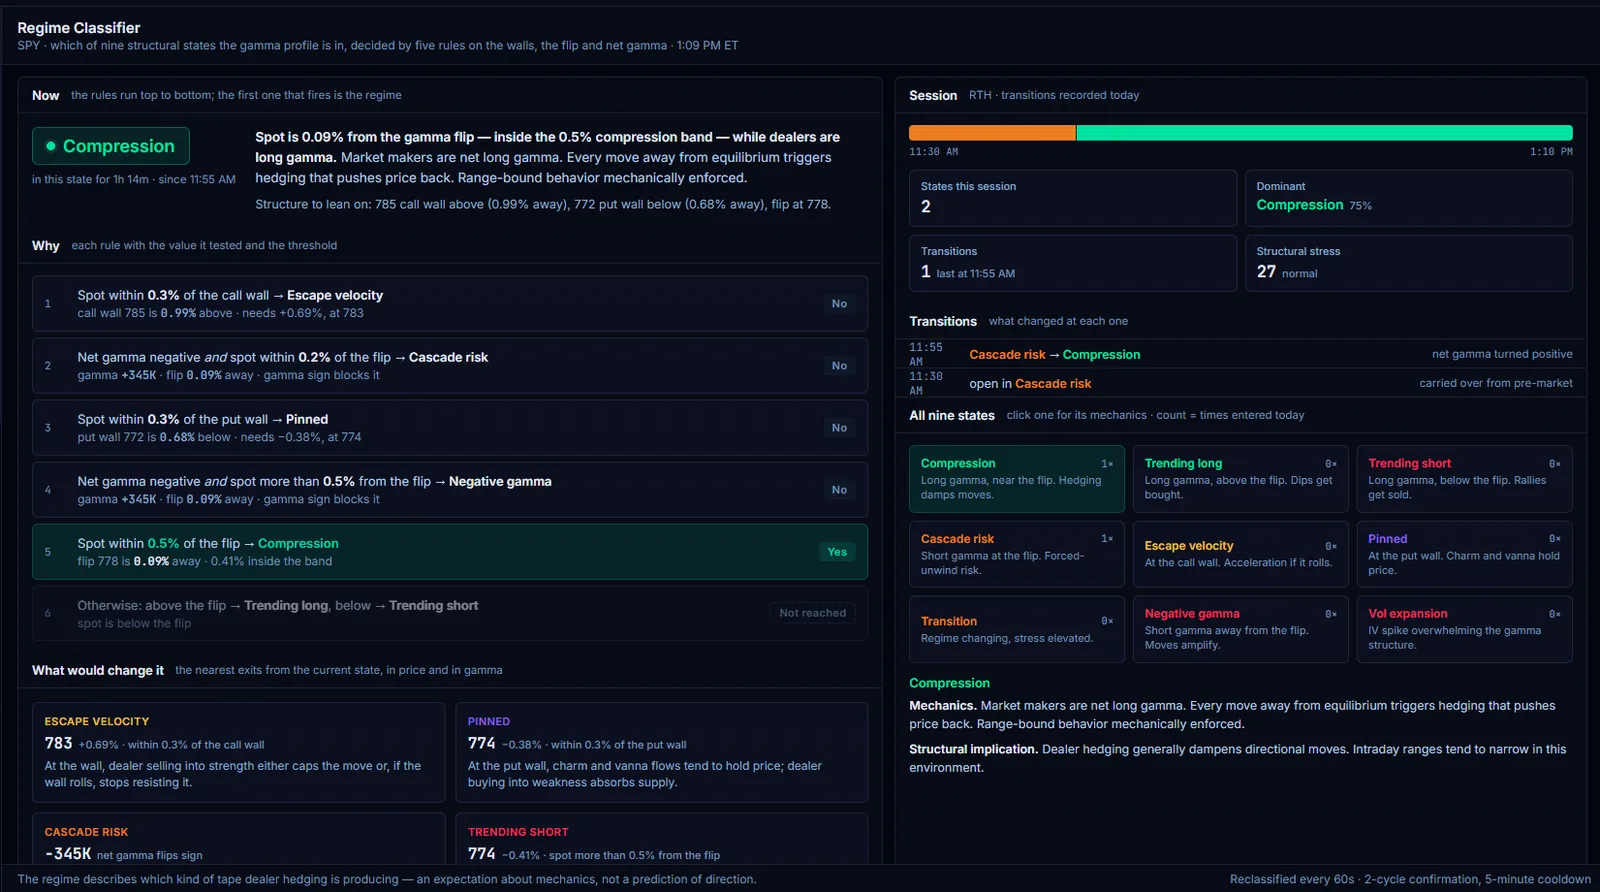
- Now — the current regime, how long it has been in force, a one-sentence condition (for example, how far spot is from the flip), and the "structure to lean on": the nearest call wall, put wall and flip.
- Why — the rule ladder. Rules are checked top to bottom; the first one that passes sets the regime. Each rule shows its live value and how far it is from passing.
- What would change it — the specific price or gamma change that would move the regime, with the level to watch.
- Session — a timeline of today's regimes plus tiles for states this session, the dominant state and its share of time, number of transitions, and structural stress.
- Transitions — every change today with its reason. The first entry can be a state carried over from pre-market.
- All nine states — reference cards with how many times each was entered today. Click one for its mechanics.
The rule ladder (first match wins)
Hysteresis: a new regime must hold for 2 consecutive compute cycles before it is shown, and there is a 5-minute cooldown after a change. This stops the label flickering when spot sits on a boundary.
What it shows
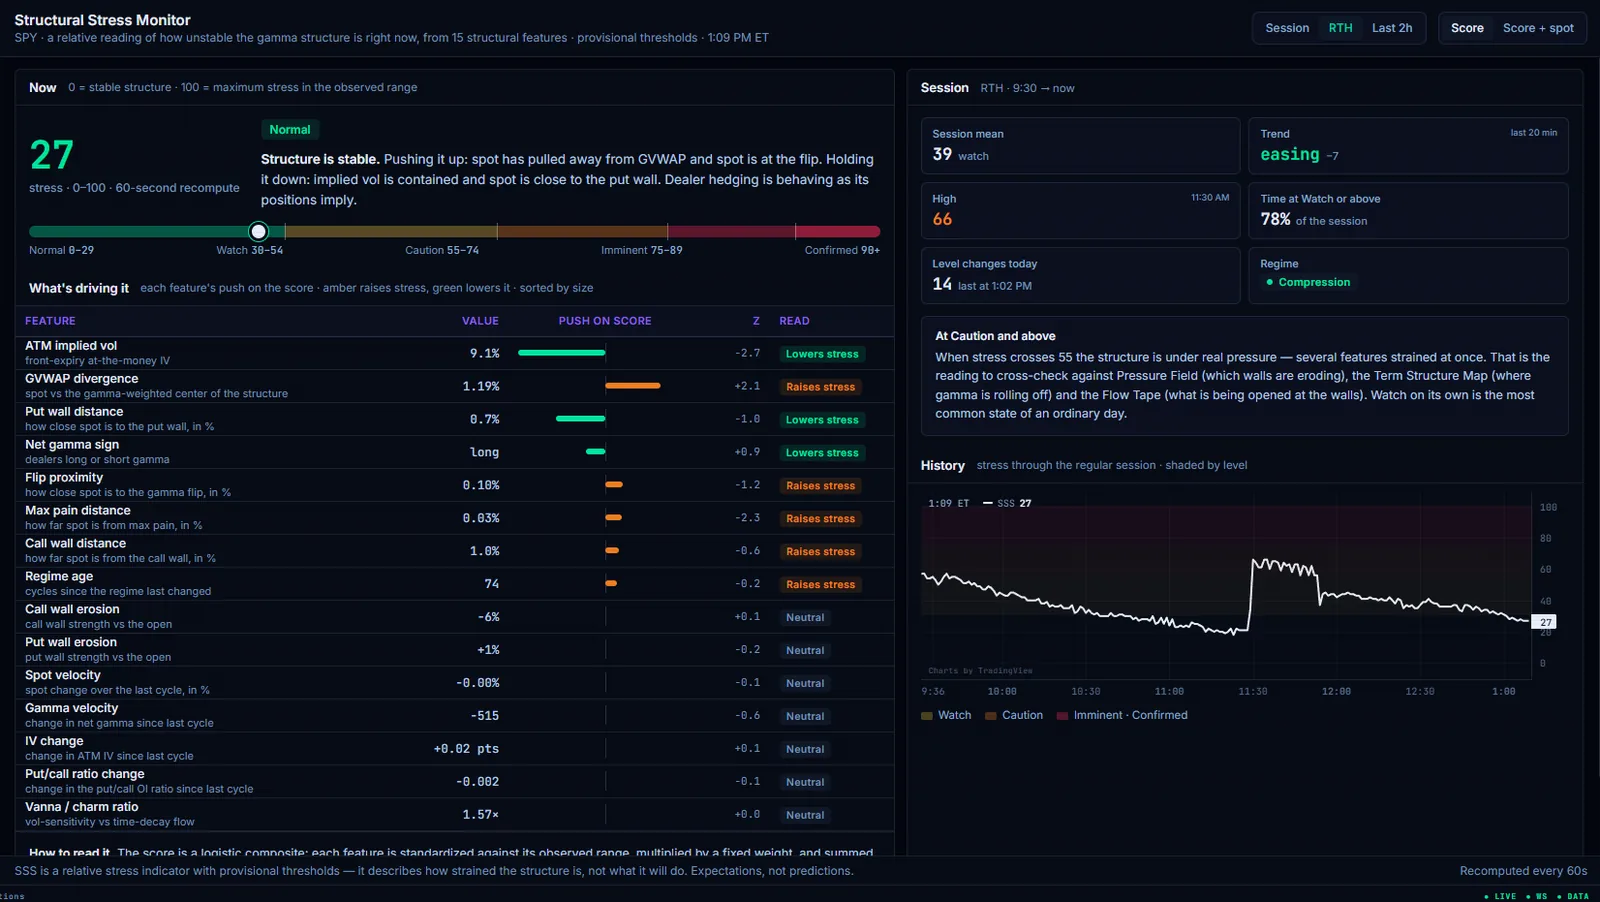
- Score 0–100 — a logistic model over 15 structural features.
- Driving table — every feature with its value, its push on the score (weight × how unusual the value is), its z-score, and a read: Raises stress, Lowers stress or Neutral. Sorted by size, so the top rows tell you why stress is where it is.
- Narrative — what is pushing the score up and what is holding it down, in plain English.
- Session tiles — session mean, trend over the last 20 minutes (rising / easing), the session high and when it happened, share of the session spent at Watch or above, number of level changes, and the current regime.
- History — the score through the session with the bands shaded. Toggle Score or Score + spot, and window Session / RTH / Last 2h.
Bands
| Score | Band | Reading |
|---|---|---|
| 0–29 | NORMAL | Structure is stable. |
| 30–54 | WATCH | Some features are unusual. Keep an eye on it. |
| 55–74 | CAUTION | Several features point to strain. Levels are less reliable. |
| 75–89 | IMMINENT | Structure is under heavy strain; a regime change is more likely. |
| 90+ | CONFIRMED | Stress is at extremes; the current structure may already be giving way. |
Features
Distance to put wall and call wall, GVWAP divergence, regime age, net gamma sign, ATM implied volatility, flip proximity, max-pain distance, put-wall and call-wall erosion, spot velocity, put/call change, IV change, gamma velocity, and the vanna/charm ratio.
"Regime age" counts compute cycles since the regime last changed — one per minute during the session.
How to use it
Read the score together with the regime. Watch is the most common reading on an ordinary day. Once stress crosses 55 (Caution), cross-check the Pressure Field (which walls are eroding), the Term Structure Map (where gamma is rolling off) and the Flow Tape (what is being opened at the walls). A long-gamma regime with low stress is the most reliable setting for fading levels. Rising stress in a long-gamma regime is the earliest warning that the dampening may not last. Open the driving table to see which features are responsible — wall erosion and flip proximity mean something different from an IV spike.
What it shows
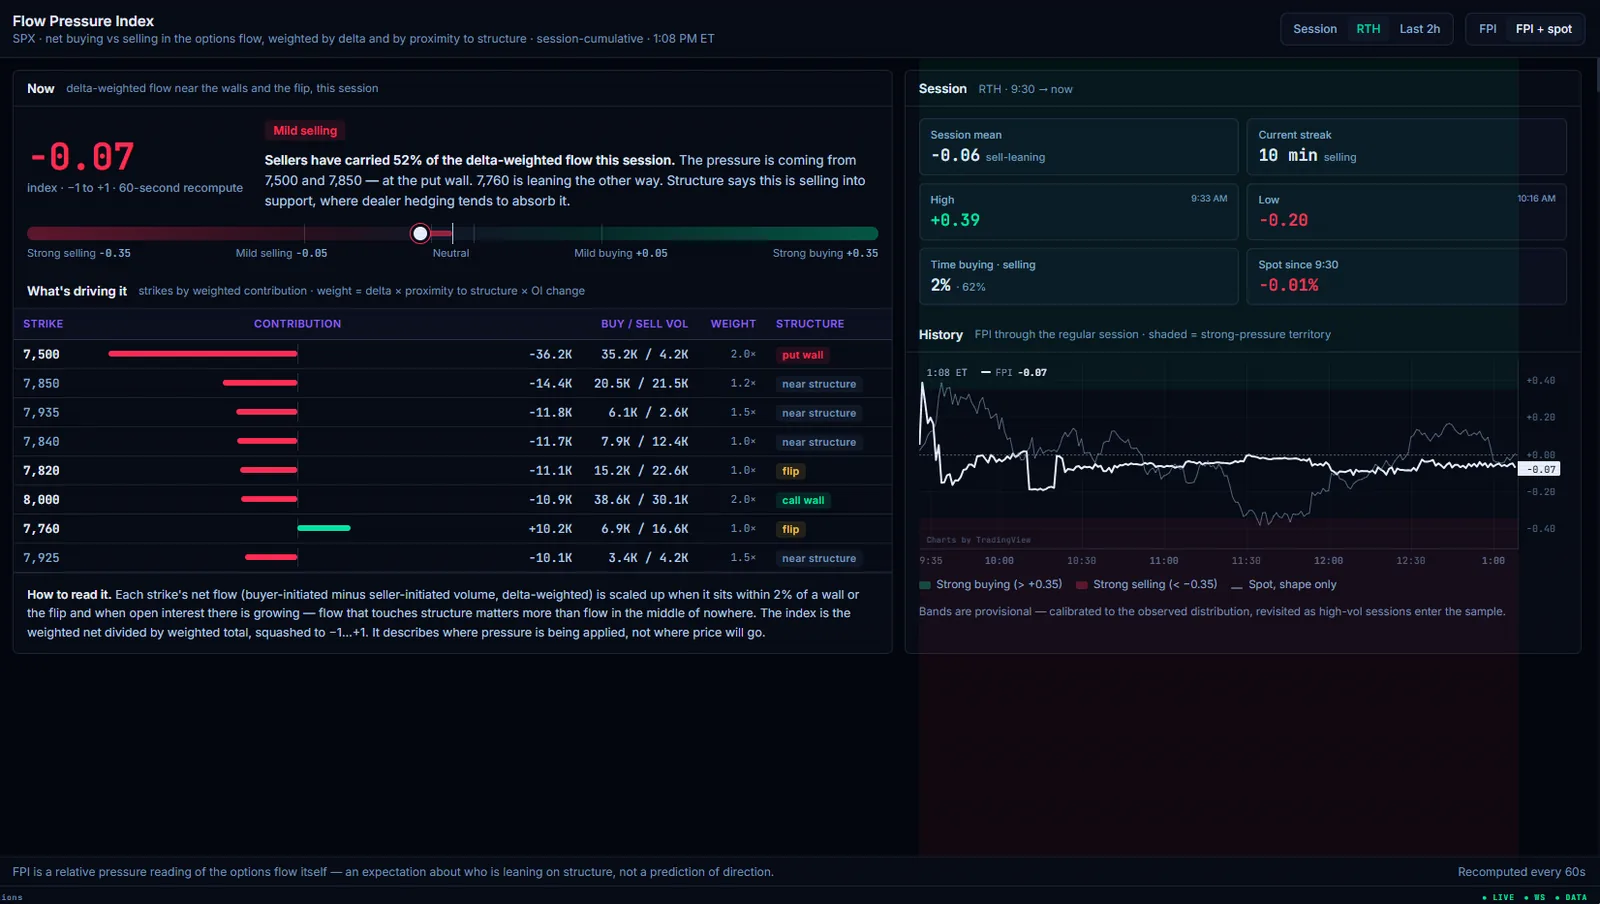
- FPI value from −1 to +1. Positive means flow is creating net dealer buying pressure; negative means net selling pressure.
- Narrative — which strikes the pressure is coming from and how that relates to structure.
- What's driving it — the eight strikes contributing most, with buyer vs seller volume, the weight applied, and a structure tag (put wall, call wall, flip, near structure).
- Session tiles — session mean, current streak (how long it has leaned one way), session high and low with times, share of time buying vs selling, and spot change since 9:30.
- History — FPI through the session with strong-pressure zones shaded. Toggle FPI or FPI + spot; window Session, RTH or Last 2h.
- A divergence card appears when FPI and price move in opposite directions.
How it is weighted
Each strike's net flow (buyer-initiated minus seller-initiated volume) is weighted by delta, by how close the strike is to the call wall or put wall (within 0.5% counts 2.0×, within 1% counts 1.5×, within 2% counts 1.2×), and by whether open interest there is growing. The index is the weighted net divided by the weighted total, so it always sits between −1 and +1. It recomputes every 60 seconds. Flow that touches structure matters most because that is where hedging concentrates.
| FPI | Reading |
|---|---|
| above +0.35 | Strong buying pressure |
| +0.05 to +0.35 | Mild buying pressure |
| −0.05 to +0.05 | Neutral |
| −0.35 to −0.05 | Mild selling pressure |
| below −0.35 | Strong selling pressure |
How it is calculated
- Daily: the at-the-money straddle for the nearest expiry at the strike closest to the anchor (the prior close). When the nearest expiry is further out, the straddle is scaled by √(1 / trading days to expiry). If a straddle is not available it falls back to implied volatility × 0.7979.
- Weekly: fixed Monday–Friday from the prior Friday's close to the following Friday's straddle.
- Monthly: the standard third-Friday cycle.
- Time to expiry is fractional, so the range shrinks correctly through the day.
Budget used
| Used | Label | Reading |
|---|---|---|
| < 70% | ROOM TO RUN | Price has used less than 70% of the priced move. |
| 70–100% | NEARING THE EDGE | Approaching the priced range. |
| > 100% | BEYOND THE RANGE | Moved further than options priced. |
What it shows
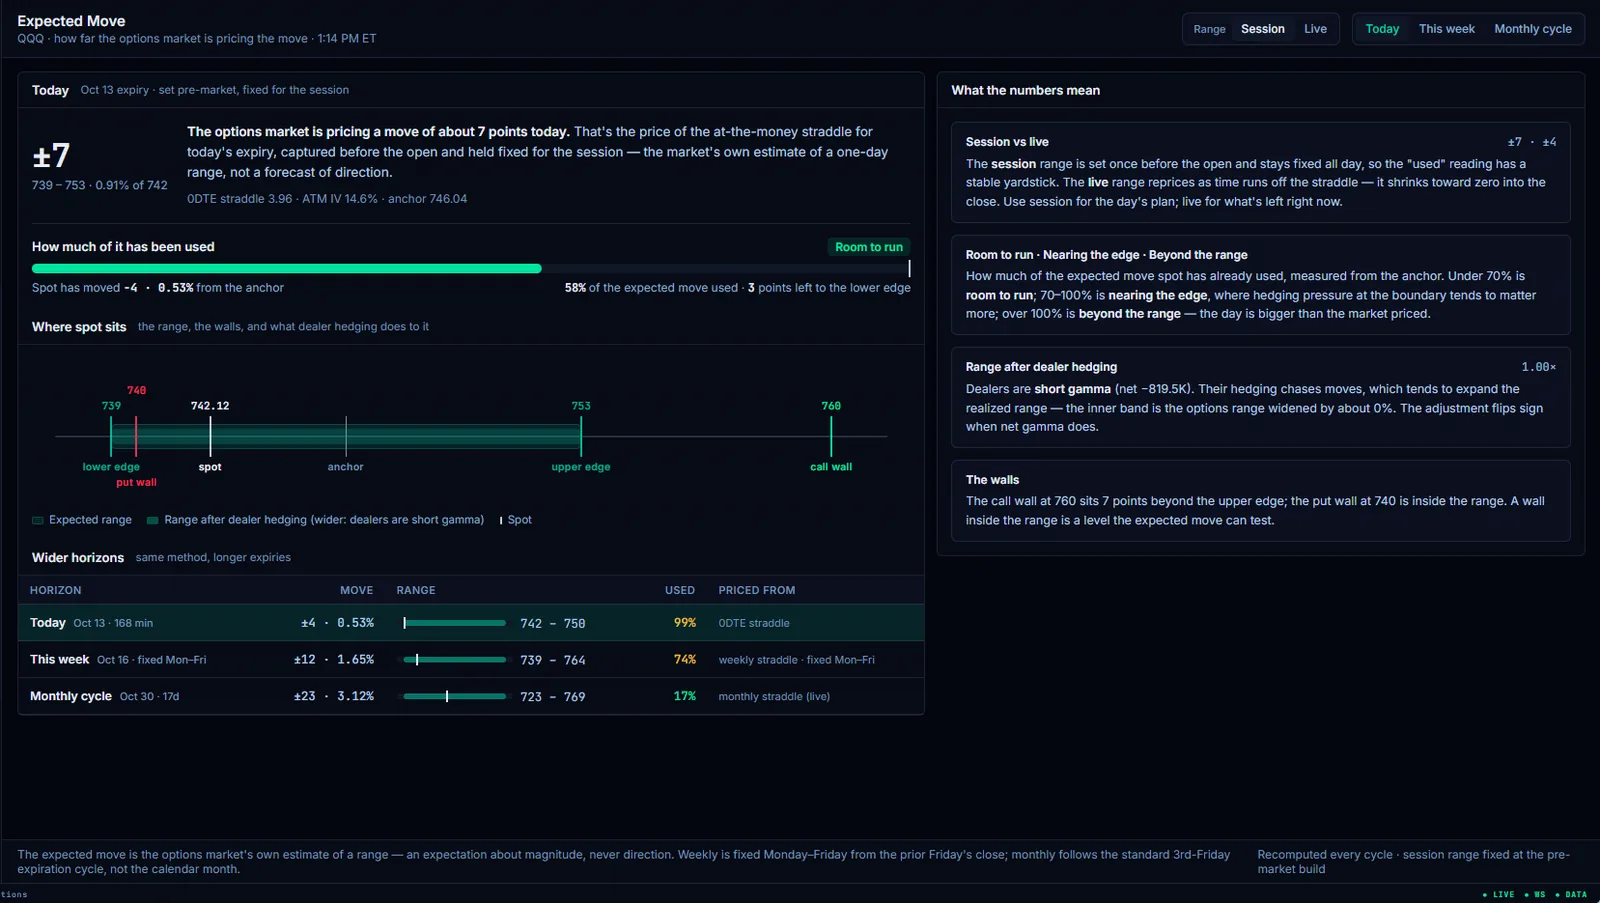
- Today — the expected move in points and percent, the range, and what it was priced from (the 0DTE straddle, ATM IV and the anchor price). The session range is set pre-market and fixed for the session.
- How much has been used — distance from the anchor, percent of the move used, and points left to the nearest edge.
- Where spot sits — the lower edge, upper edge, anchor, spot, put wall and call wall on one line.
- Wider horizons — today, this week and the monthly cycle, each with its move, range, percent used and what it was priced from. Until a fixed 3rd-Friday band has been captured, the monthly row shows Month ahead, priced from the nearest expiry two to six weeks out.
- What the numbers mean — session vs live, the budget labels, and where the walls sit relative to the range.
Range toggles Session (fixed all day — a stable yardstick for "used") and Live (reprices as time runs off the straddle and shrinks toward zero into the close). Use session for the day's plan and live for what is left right now. Horizon switches between Today, This week and Monthly cycle.
What it shows
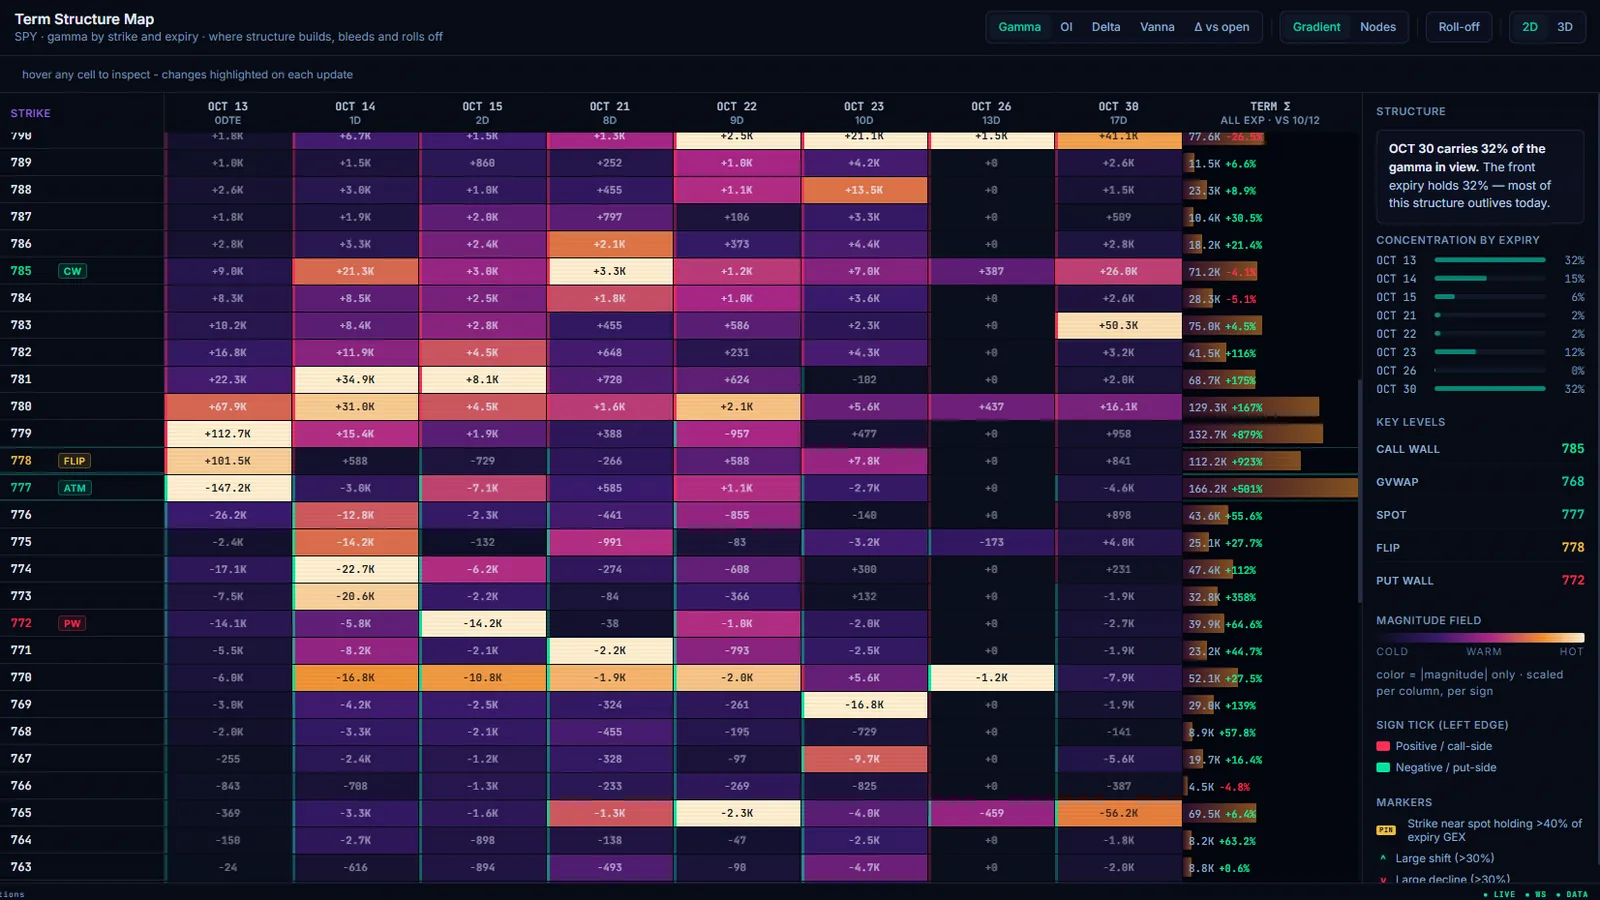
A heatmap of strikes (50 each side of spot) against expiries (up to 3 short-dated and 5 longer-dated). Modes: Gamma, OI, Delta, Vanna and Δ vs open. Render as Gradient or Nodes, in 2D or 3D.
- Cell color shows size only (cold to hot, scaled per column and per sign). The sign is shown by a small tick on each cell's left edge — positive / call-side or negative / put-side — and by the +/− on the value.
- TERM Σ — each strike's total across all expiries, with its change vs the prior day.
- Strike labels mark CW, FLIP, ATM and PW.
- Markers — PIN (a strike near spot holding more than 40% of its expiry's GEX), large shift (more than 30%) and large decline (more than 30%).
- Side panel — a one-line structure read (for example "OCT 30 carries 32% of the gamma in view"), concentration by expiry, and key levels: call wall, GVWAP, spot, flip and put wall.
- Roll-off — shows the structure as it would look after the nearest expiry is removed.
- Hover any cell to inspect it; changes are highlighted on each update.
How to use it
Look for exposure that is concentrated in one expiry. If the call wall lives almost entirely in tomorrow's expiry, it will be gone after tomorrow. Use Roll-off preview before expiry days to see which levels survive.
What it shows
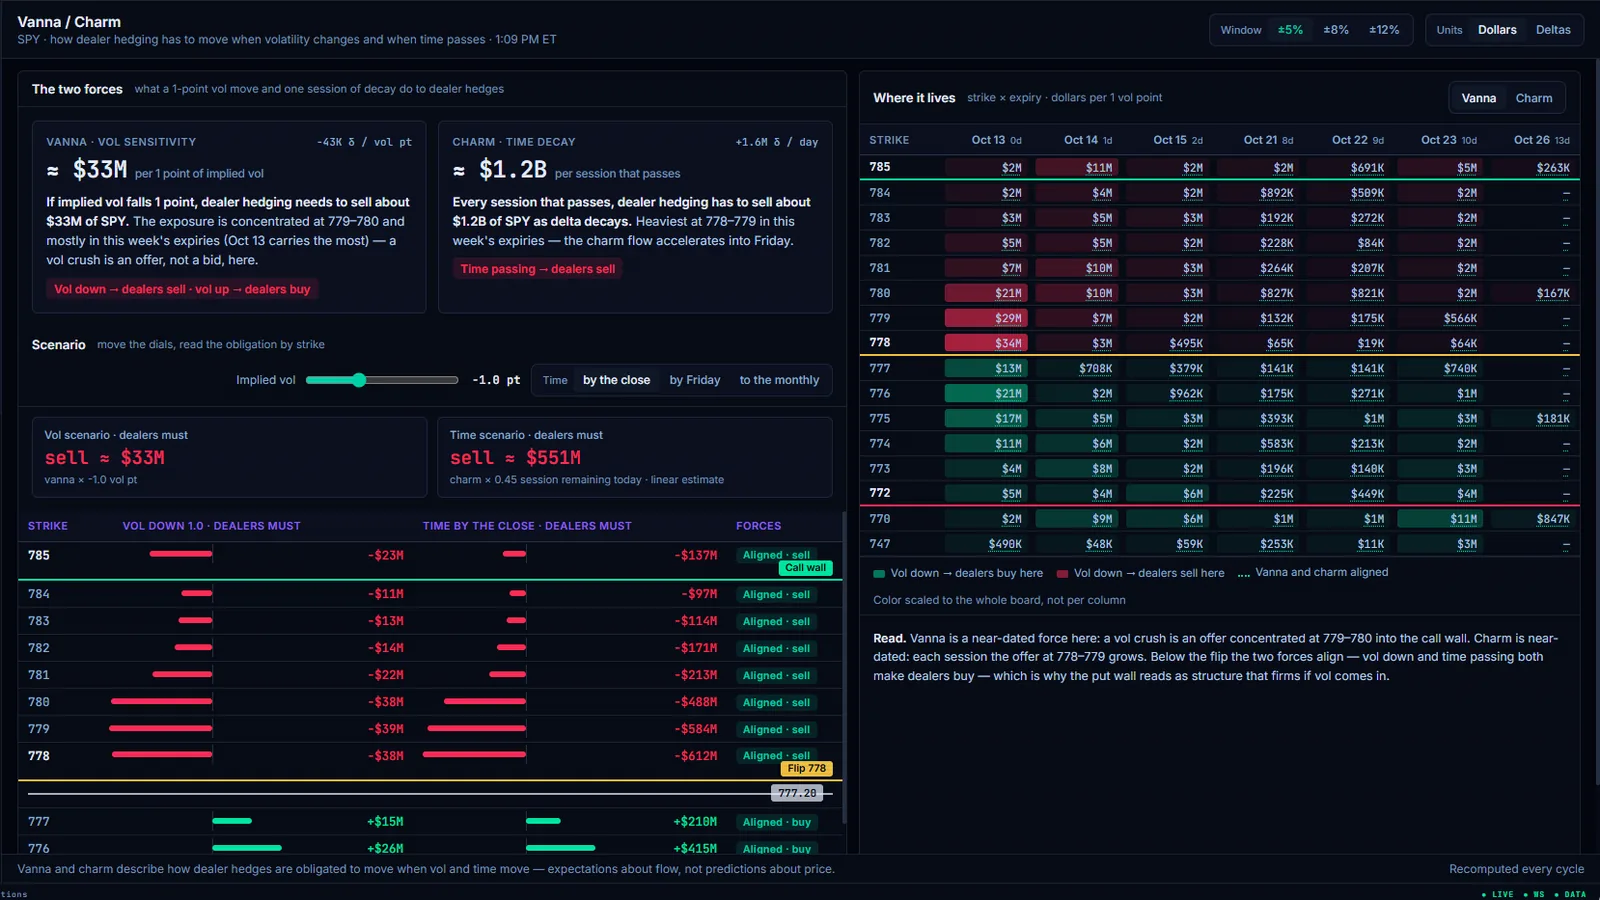
- Window ±5%, ±8% or ±12% around spot. Units: dollars or deltas.
- The two forces — vanna (what a 1-point vol move does to dealer hedges) and charm (what one session of time decay does), each in dollars with a plain-English read such as "vol down → dealers sell".
- Scenario — move the implied-vol slider (−3 to +3 points) and pick a time horizon: by the close, by Friday or to the monthly. Shows the estimated dealer buying or selling needed (a linear estimate).
- Strike table — what dealers must do at each strike under the scenario, tagged Aligned · buy/sell (vanna and charm push the same way) or Opposed, with wall and flip markers and spot.
- Where it lives — a strike × expiry grid for vanna or charm, colored across the whole board, followed by a Read paragraph.
- When implied volatility falls (often after events), vanna tends to make dealers buy back short hedges — a source of "vol-crush rallies."
- Charm grows as expiry approaches. Into monthly expiry, charm flows can add a steady bid or offer that does not need any price move to appear.
- Strikes where vanna and charm are Aligned carry the most reliable drift; Opposed strikes tend to cancel.
What it shows
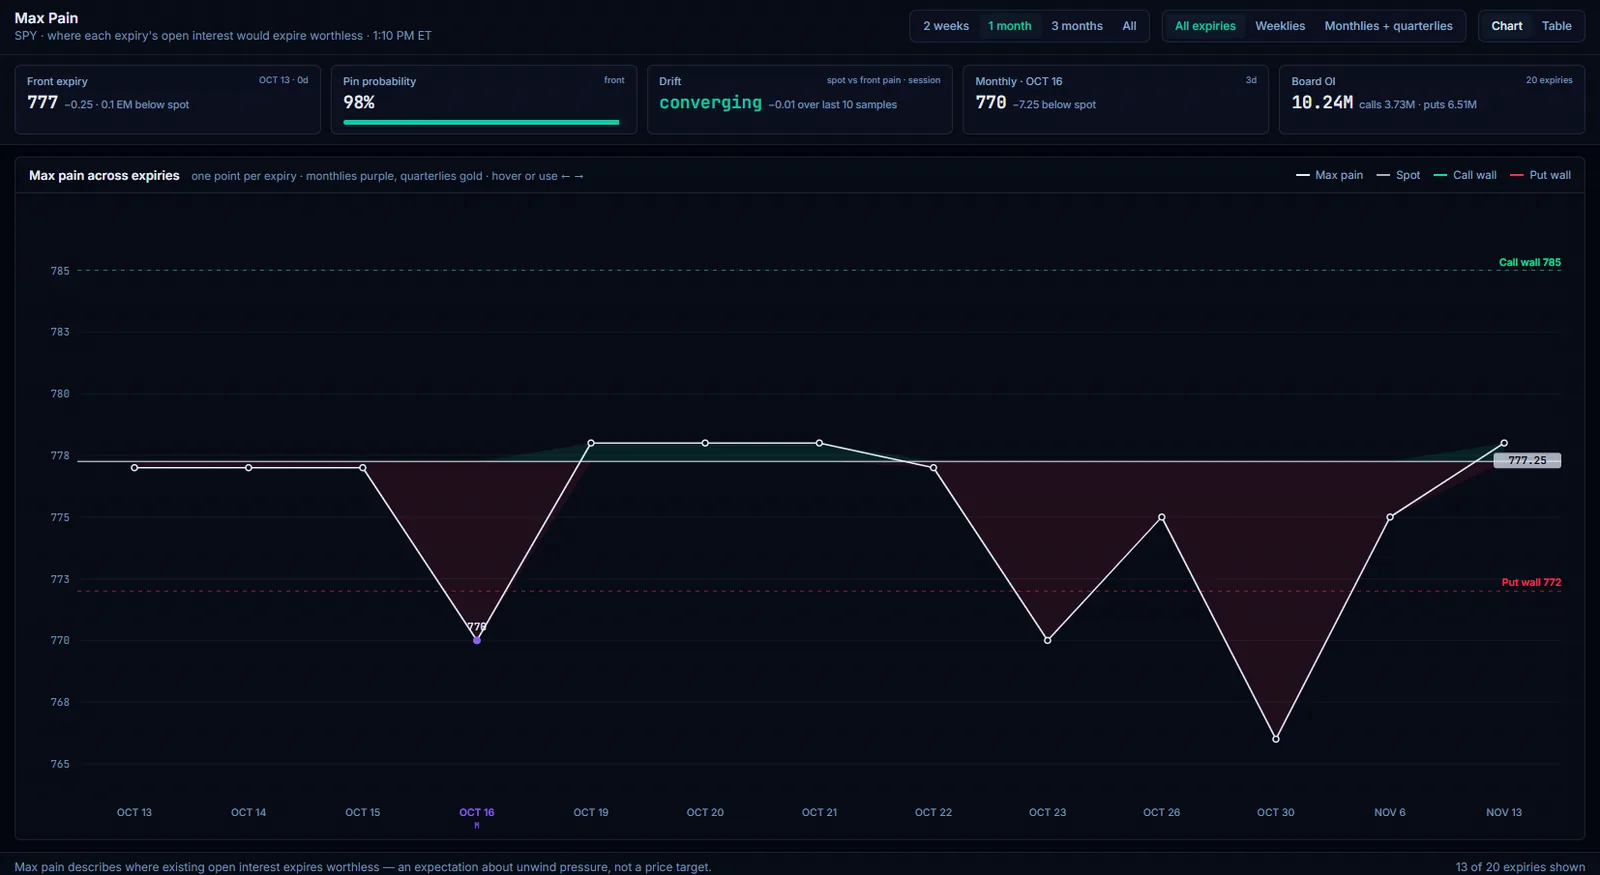
- Max pain for every expiry, its distance from spot (in points and in expected moves), and an estimated pin probability that rises as distance and days to expiry shrink.
- Tiles — front-expiry max pain and its distance from spot, pin probability for the front expiry, drift (whether spot is converging toward or diverging from front-expiry max pain this session), the next monthly's max pain, and total board OI.
- Max pain across expiries — one point per expiry against spot, call wall and put wall. Monthlies are marked purple and quarterlies gold. Hover or use ← → to step through.
- Controls: range (2 weeks, 1 month, 3 months, All), kind (All expiries, Weeklies, Monthlies + quarterlies), view (Chart or Table).
What it shows
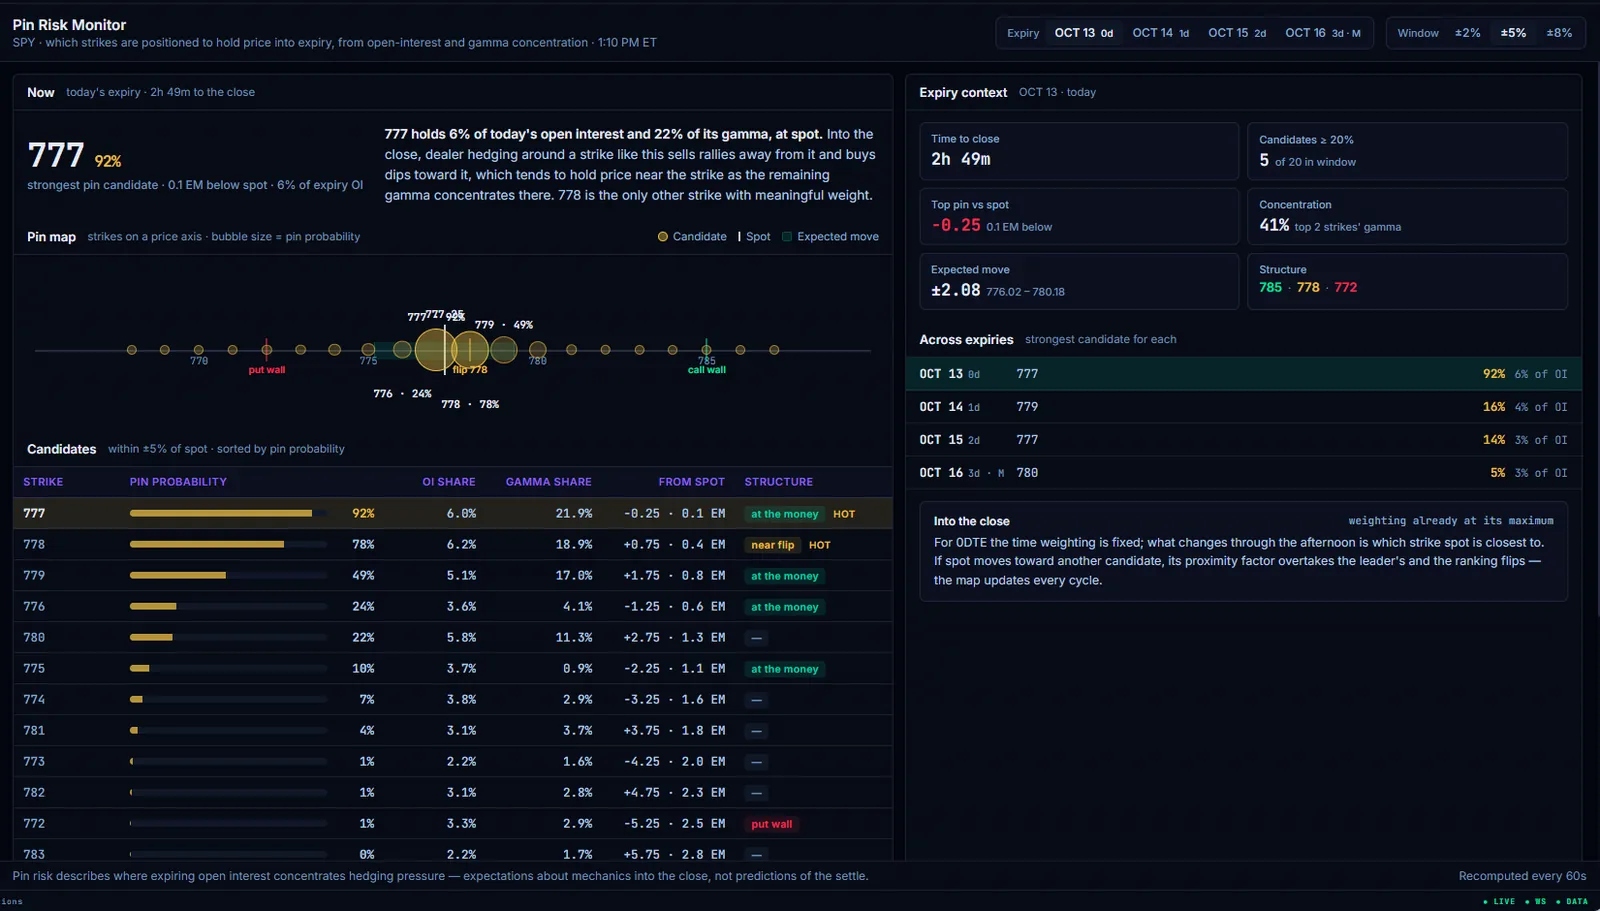
- Pin probability per strike for the chosen expiry, combining the strike's share of open interest, its share of gamma, its proximity to spot, and days to expiry. Strikes above 50% are marked HOT.
- Now — the strongest candidate, its probability, distance from spot in expected moves, and a plain-English read.
- Pin map — bubbles sized by probability along the price axis, with spot, the walls, the flip and the expected move.
- Candidates — pin probability, OI share, gamma share, distance from spot (points and expected moves), and structure tags (at the money, near flip, put wall, call wall).
- Expiry context — time to close, number of candidates at 20% or more, top pin vs spot, concentration in the top two strikes, the expected move, and the structure levels.
- Across expiries — the strongest candidate for each upcoming expiry (M marks the monthly).
- Expiry picker (0d, 1d, 2d …) and window ±2%, ±5% or ±8%.
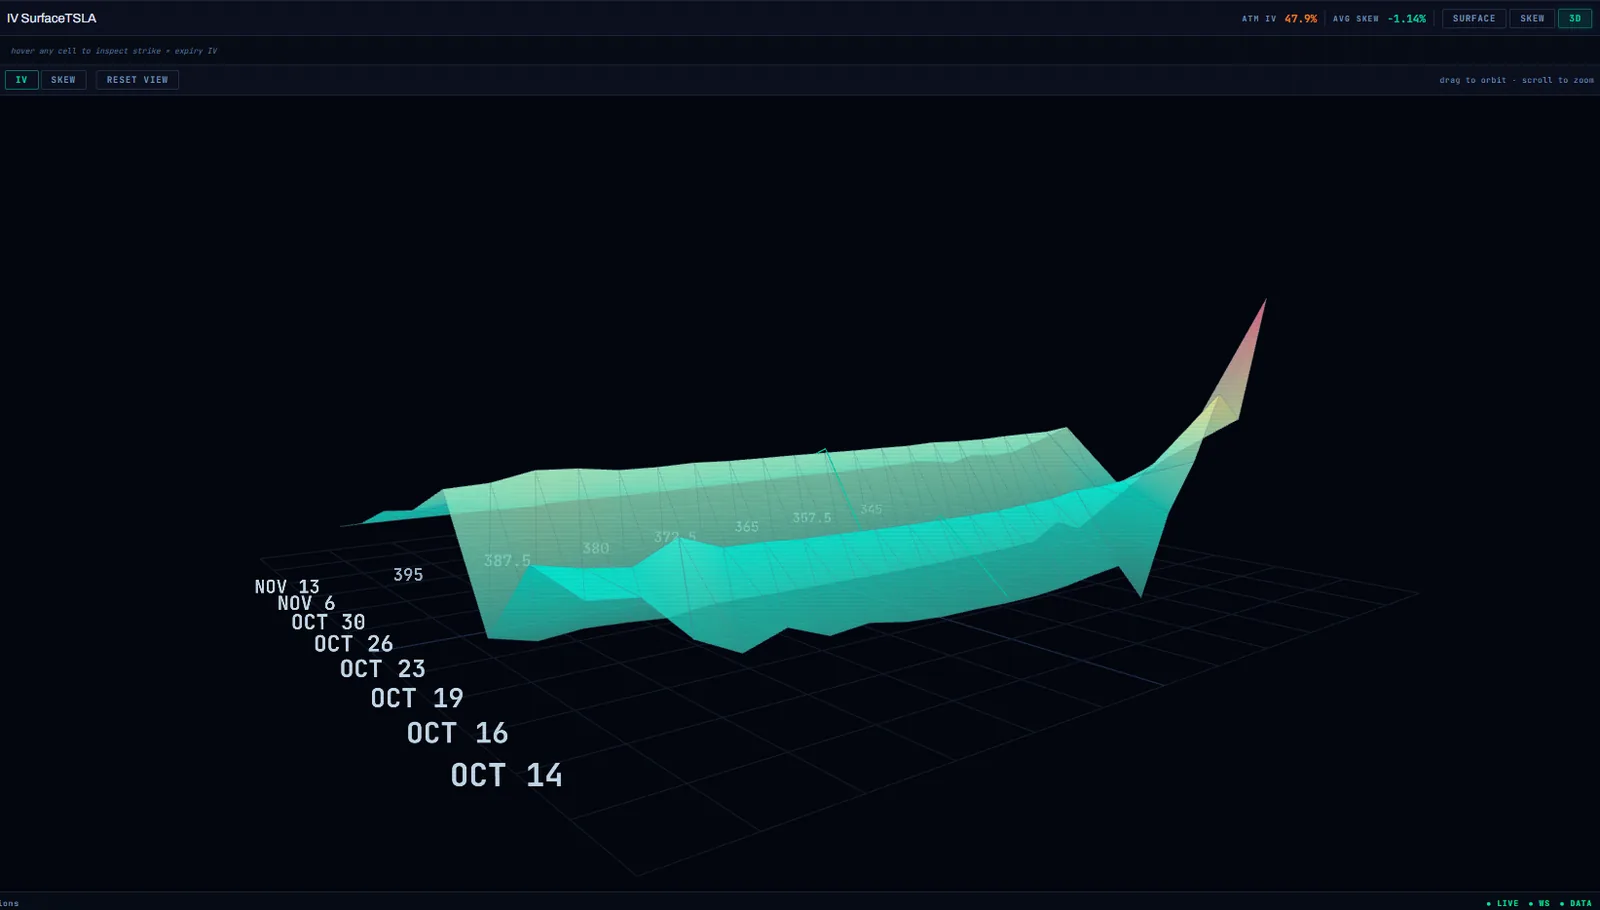
Views: SURFACE (strike × expiry heatmap — hover a cell to inspect it), SKEW (per-expiry smile) and 3D. The header shows ATM implied volatility and average skew. In 3D, switch between IV and SKEW, drag to orbit, scroll to zoom, and use Reset view to recenter.
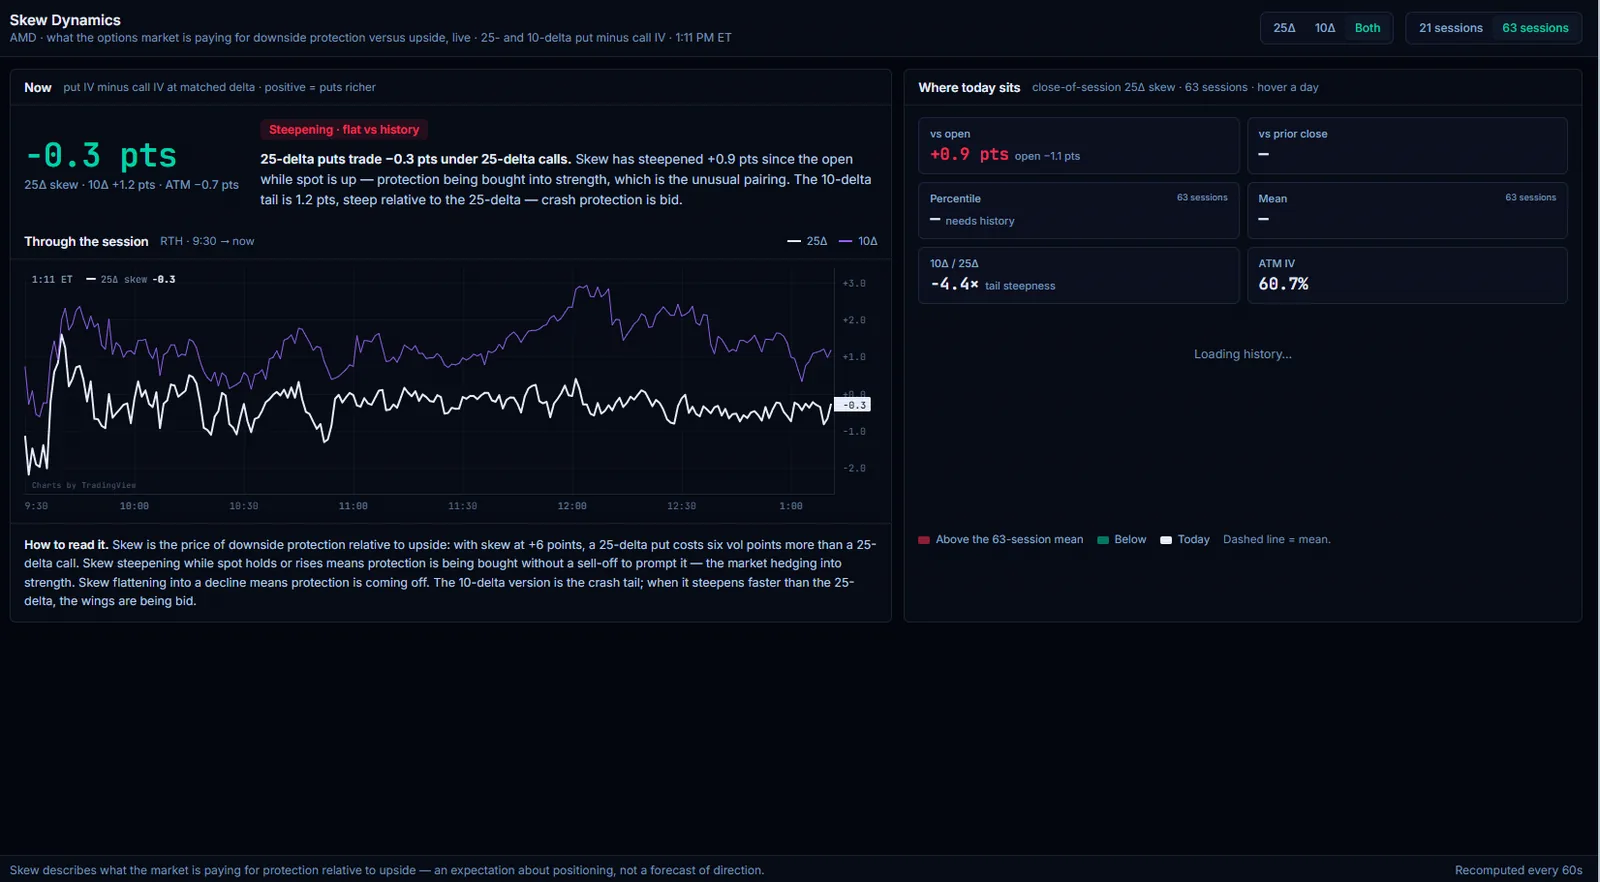
- Now — put IV minus call IV at matched delta (positive = puts richer), shown for 25Δ, 10Δ or both, with ATM IV and a plain-English read.
- Through the session — 25Δ and 10Δ skew since 9:30.
- Where today sits — change vs the open and vs the prior close, percentile (over 63 sessions), mean (over 21 or 63 sessions), the 10Δ/25Δ ratio, and ATM IV, plus a daily history chart.
- Steepening / Flattening when skew changes by more than 0.3 points.
- 10Δ/25Δ ratio — how steep the tail is. Above 2.2 means tail protection is unusually expensive relative to near-the-money puts; below 1.4 means tails are cheap. Read it only when 25Δ skew is positive; when 25Δ is near zero or negative the ratio is not meaningful.
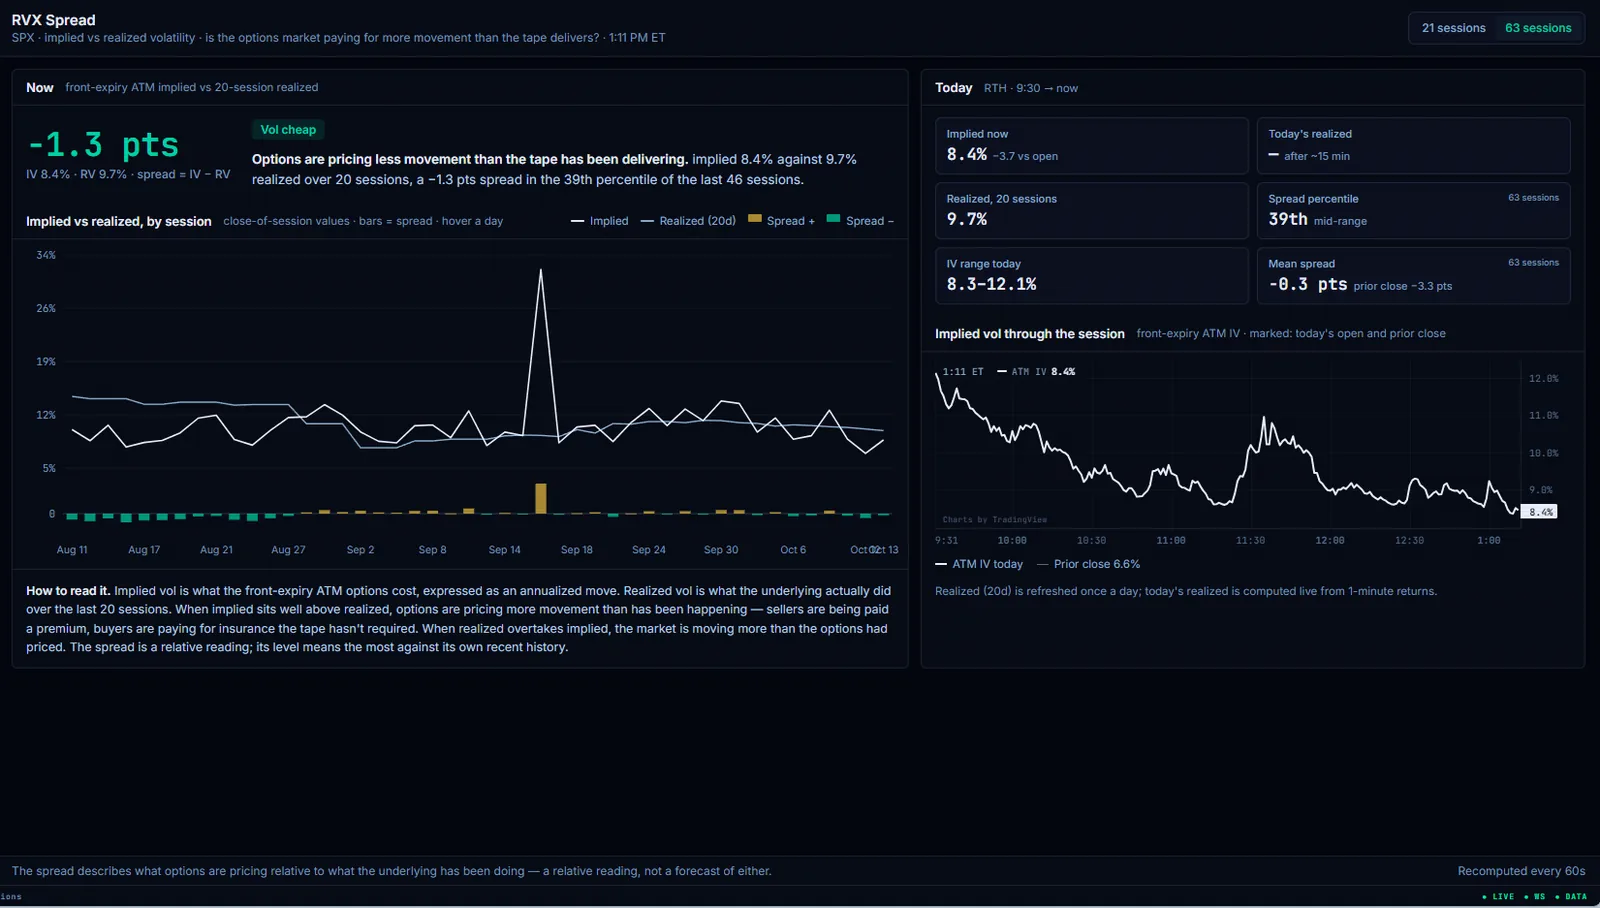
- Now — front-expiry ATM implied volatility minus 20-session realized volatility, with a plain-English read. Vol rich above +3 points, Vol cheap below −1 point.
- Implied vs realized, by session — daily implied and realized lines with the spread as bars. Hover a day.
- Today — implied now (and change vs open), today's realized (from 1-minute returns, after about 15 minutes), 20-session realized, spread percentile, today's IV range, and mean spread over 21 or 63 sessions.
- Implied vol through the session — ATM IV since the open, with the prior close for reference.
What it shows
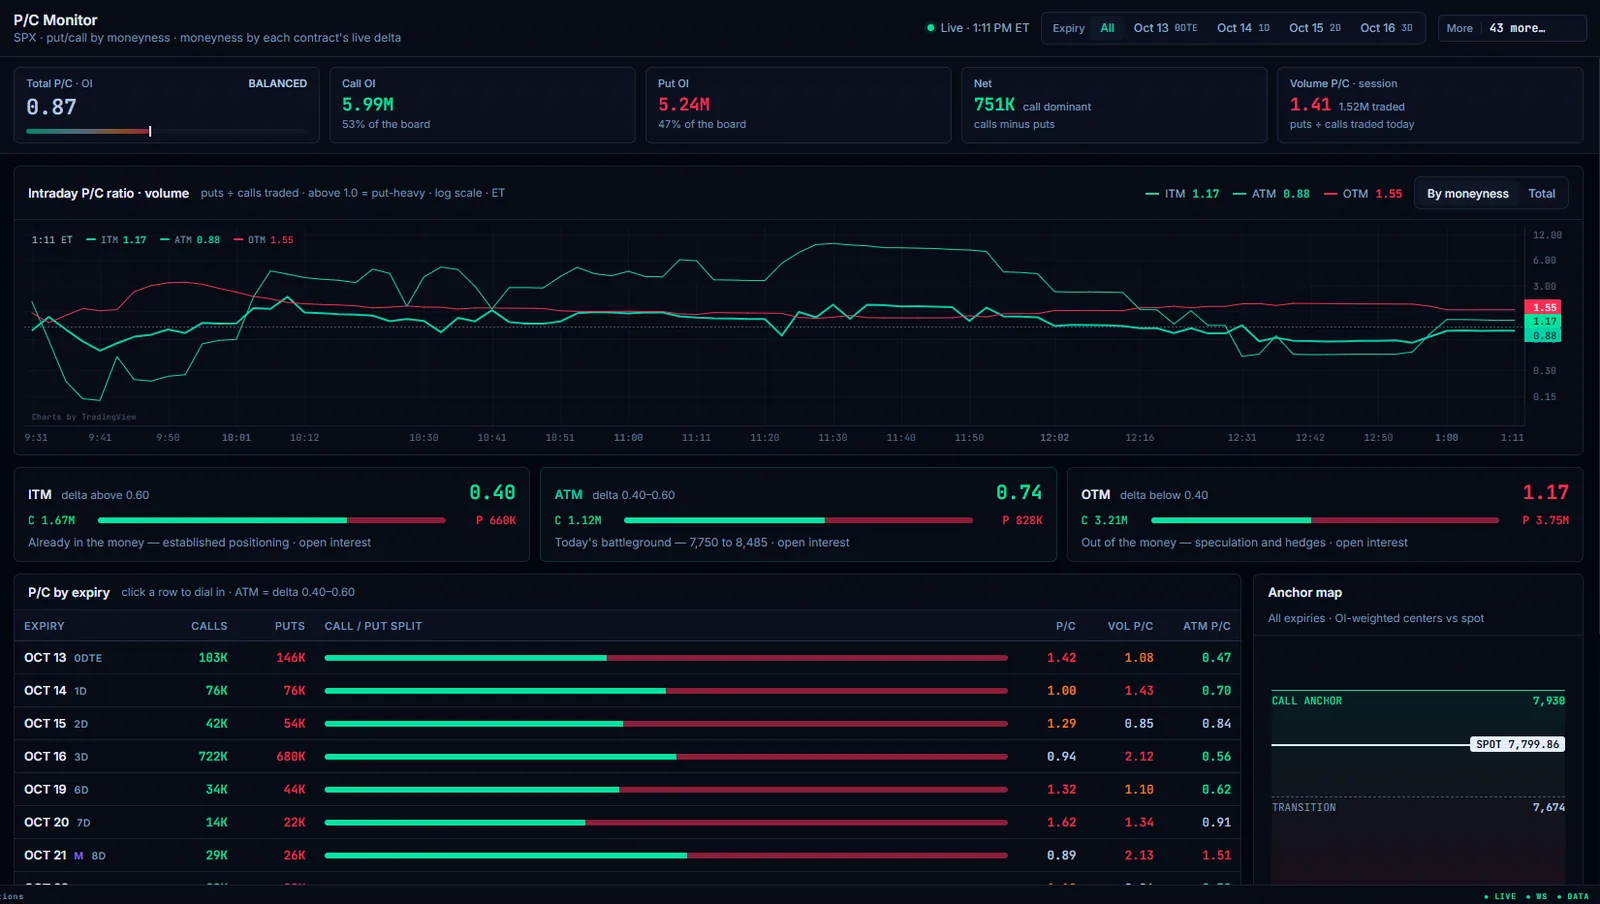
- Stat strip — total put/call open-interest ratio with its reading: PUT HEAVY at 1.2 or above, PUT LEAN 1.0–1.2, BALANCED 0.8–1.0, CALL HEAVY below 0.8 (Command's P/C tile uses its own simpler cut-offs), call OI, put OI, net (calls minus puts), and the session's volume put/call ratio.
- Intraday P/C ratio · volume — puts ÷ calls traded, sampled every 2 minutes on a log scale. Above 1.0 is put-heavy. Show it by moneyness (ITM, ATM, OTM) or total.
- Moneyness cards — call vs put open interest and the P/C ratio for ITM (delta above 0.60, established positioning), ATM (delta 0.40–0.60, today's battleground, shown as a price range) and OTM (delta below 0.40, speculation and hedges). Moneyness uses each contract's live delta.
- P/C by expiry — calls, puts, the split, OI P/C, volume P/C and ATM P/C per expiry. Click a row to dial in.
- Expiry dial-in — All, the next four expiries, or More.
- Anchor map — OI-weighted centers of call and put positioning relative to spot, with a 5-day migration view.
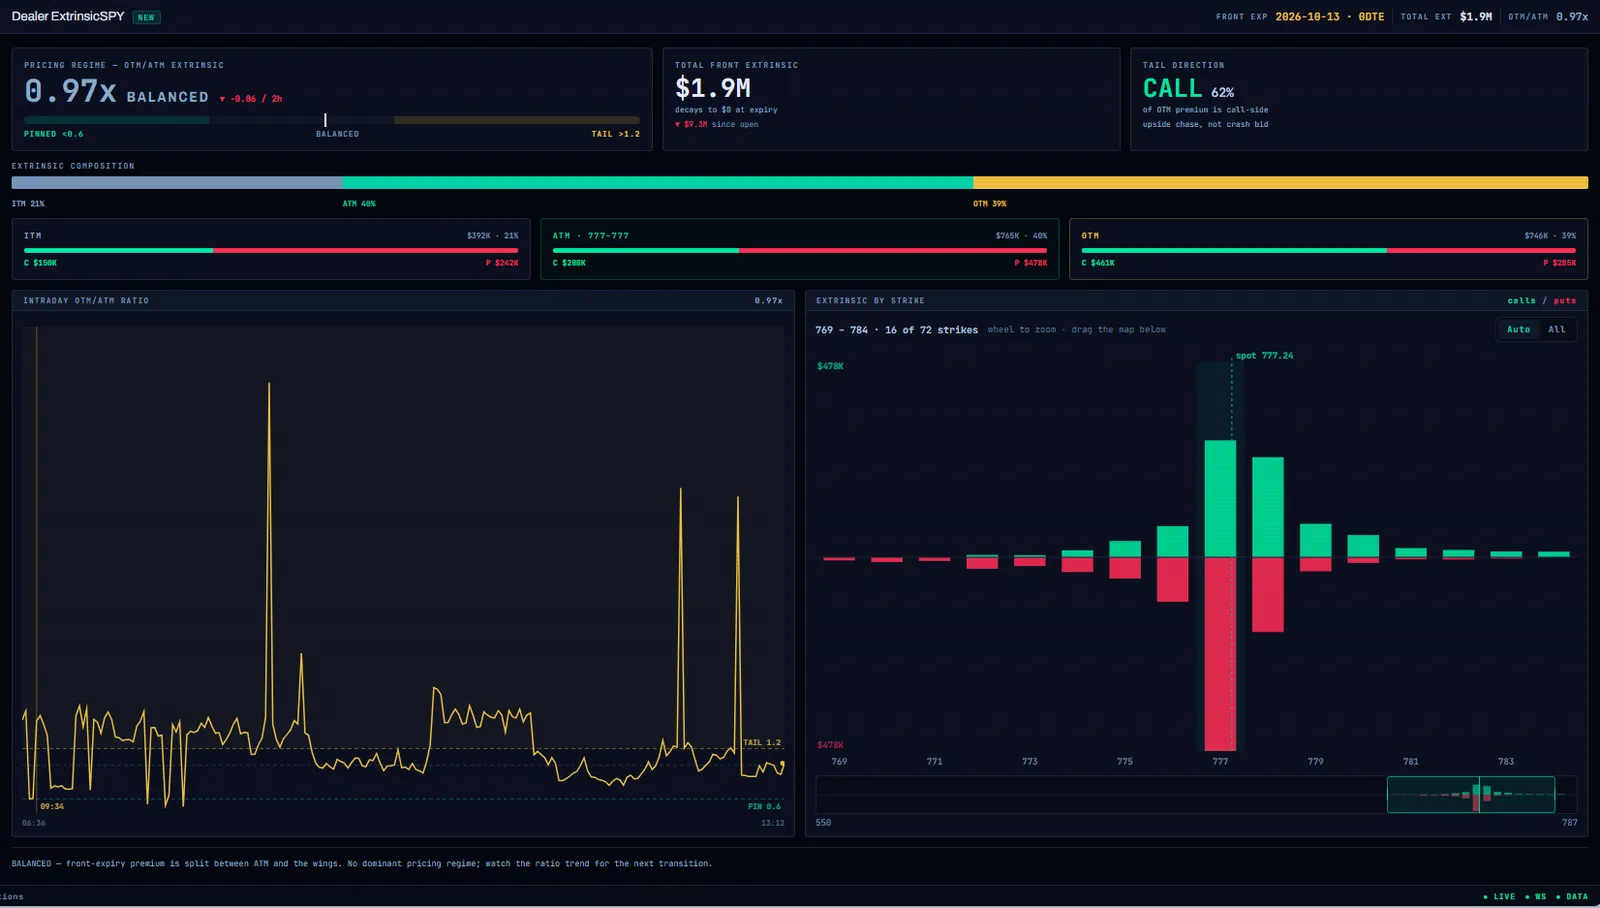
- Pricing regime — the front expiry's OTM/ATM extrinsic ratio and its change over the last 2 hours. PINNED below 0.6 (value concentrated at the money), BALANCED 0.6–1.2, TAIL above 1.2 (value concentrated away from spot). Thresholds are provisional.
- Total front extrinsic — the time value that decays to $0 at expiry, and its change since the open.
- Tail direction — which side holds most of the OTM premium (call-side reads as upside chase; put-side as crash bid).
- Extrinsic composition — ITM / ATM / OTM shares, each split into calls and puts.
- Intraday OTM/ATM ratio — from pre-market, with the PIN and TAIL lines.
- Extrinsic by strike — calls above, puts below. Wheel to zoom, drag the minimap, or choose Auto / All.
What it shows
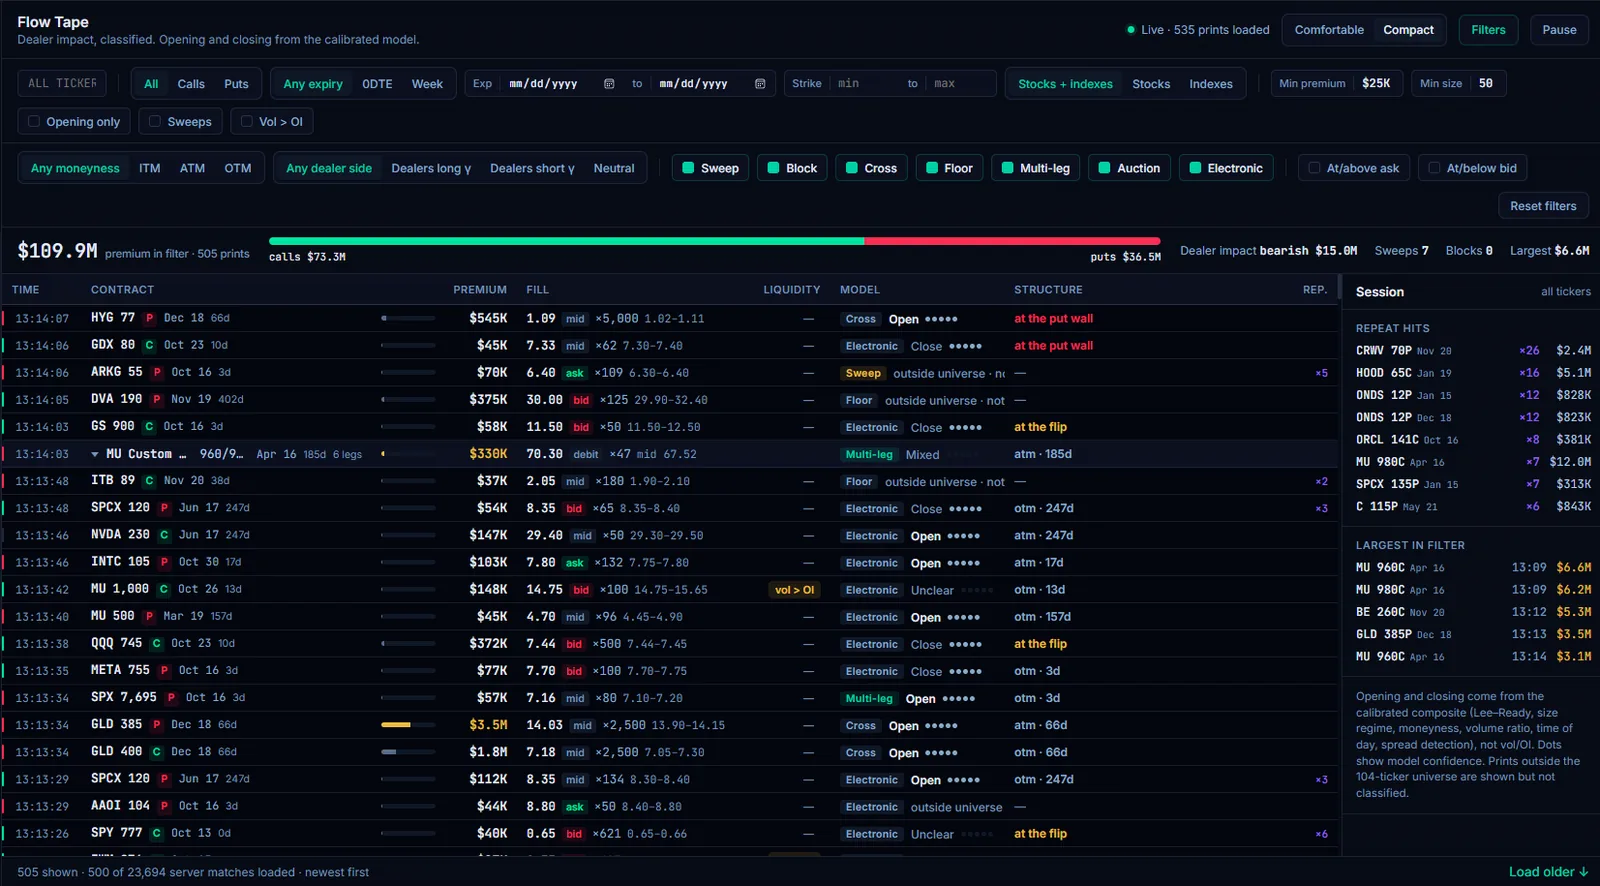
A live tape of options prints, newest first, with each print classified. Prints outside the 150+ ticker universe are shown but not classified.
| Column | Meaning |
|---|---|
| Time | Exchange time, Eastern. |
| Contract | Ticker, expiry, strike, call/put. |
| Premium | Size × price × 100. |
| Fill | Price, where it traded against the quote (above ask, ask, mid, bid, below bid), size, and the bid–ask at the time. Mid prints have no inferred side. Multi-leg trades show debit or credit. |
| Liquidity | Flags unusual liquidity — chiefly Vol > OI. |
| Model | The trade type from exchange condition codes (Sweep, Cross, Floor, Multi-leg, Auction, Electronic) and the model's call: Open, Close, Mixed or Unclear, with confidence dots. A model label, not a fact. |
| Structure | Where the strike sits: at the put wall, at the call wall, at the flip, or its moneyness and days to expiry (for example "otm · 247d"). Multi-leg trades are grouped into one expandable row. |
| Rep. | How many times the same contract has printed in the loaded window. The Repeat hits panel lists the most-repeated contracts. |
- Vol > OI — a single print at least as large as the contract's existing open interest, which strongly suggests a new position.
- Filters — ticker; calls / puts; any expiry, 0DTE or this week, or a date range; strike range; stocks and/or indexes; minimum premium (default $25K) and minimum size (default 50); opening only, sweeps only, Vol > OI only; moneyness; dealer side (dealers long gamma, short gamma, neutral); trade types; at/above ask or at/below bid. Reset filters returns to defaults.
- Summary strip — premium in filter, calls vs puts, estimated dealer impact (bullish or bearish, in dollars), sweep count and the largest print.
- Session panel — Repeat hits (contracts printing again and again) and Largest in filter, across all tickers.
- Comfortable / Compact density, Pause to freeze the tape, and Load older to page back.
- Prints under 5 contracts are dropped. Cancelled prints are removed.
What it shows
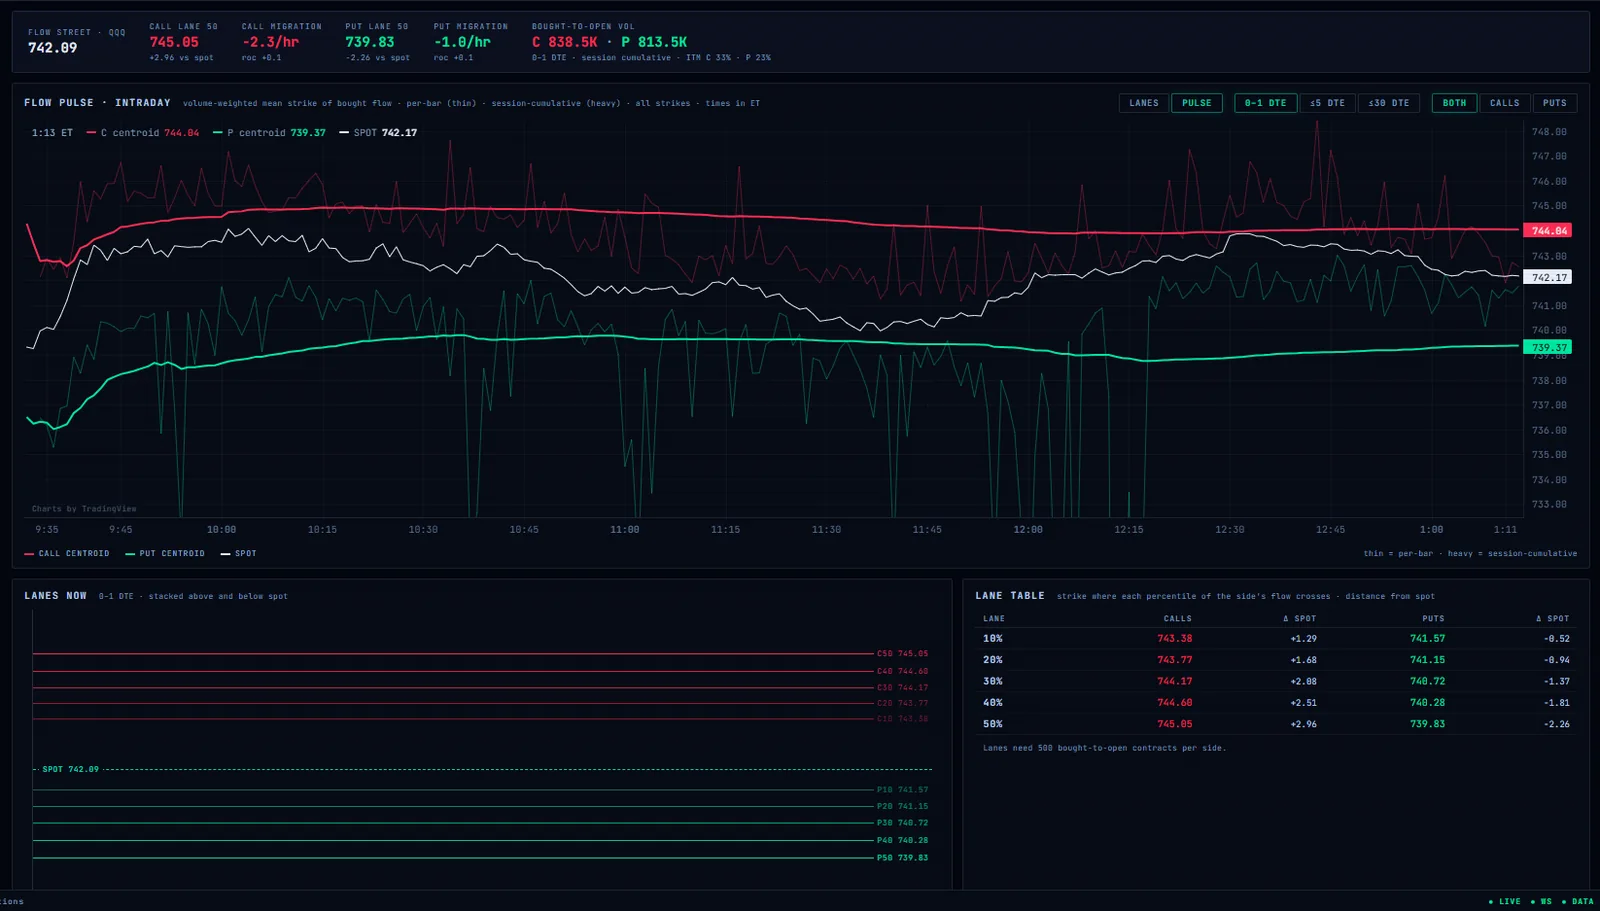
Only flow classified as bought to open (trade-side and composite signals both agree it is a buyer opening a position), in universe tickers, expiring within 30 days.
- Header — spot, the call lane 50 and put lane 50 (and their distance from spot), call and put migration in points per hour, and bought-to-open volume for calls and puts.
- Lenses: 0–1 DTE, ≤ 5 DTE or ≤ 30 DTE. Side: Calls, Puts or Both.
- LANES — intraday bands showing where call and put buying is concentrated, drawn from the 10th to 50th percentile of out-of-the-money buying (needs at least 500 contracts per side; dimmed under 1,500).
- PULSE — the volume-weighted average strike of call and put buying (the centroid), per bar (thin line) and session-cumulative (heavy line), with spot.
- Lanes now — today's call lanes (C10–C50) stacked above spot and put lanes (P10–P50) below. The Lane table lists each lane's strike and distance from spot.
What it shows
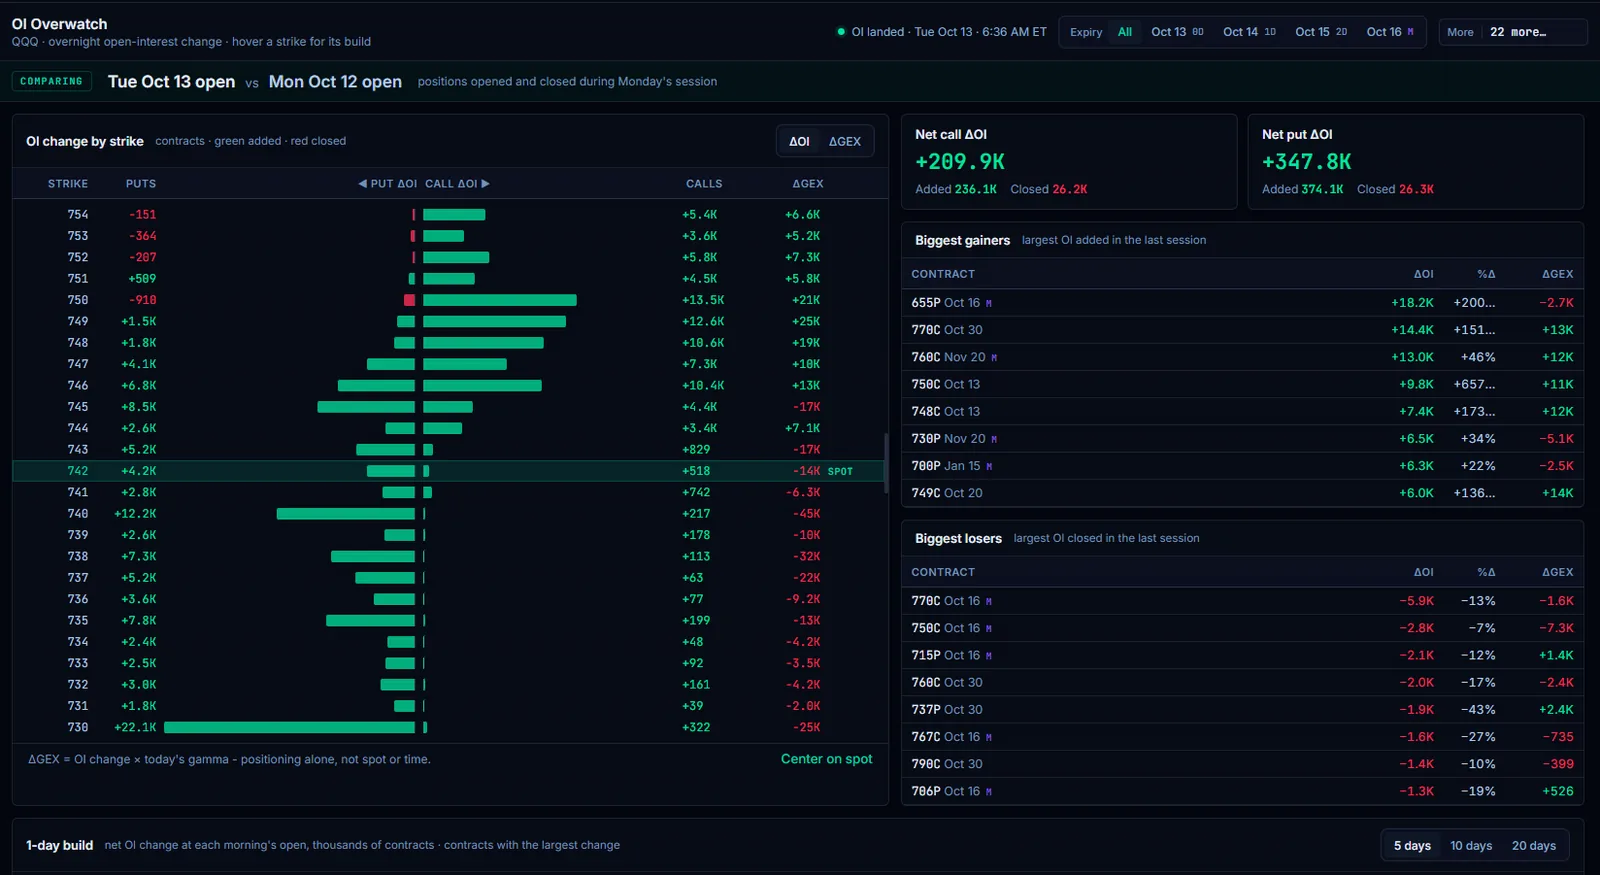
Exchanges publish open interest once a day. OI Overwatch compares the newest file with the prior one — for example "Mon open vs Fri open" shows the positions added or closed during Friday's session.
- Status — when the new file landed (for example "OI landed · 6:36 AM ET"). Capture runs 06:00–16:15 ET; data is flagged stale if the new file has not arrived by 10:30.
- Expiry dial-in — All, the next four expiries, or More.
- Net call ΔOI / Net put ΔOI — net change, with contracts added and closed.
- Biggest gainers / losers — the eight contracts with the most OI added and closed, with ΔOI, %Δ and ΔGEX (M marks monthlies).
- OI change by strike — puts to the left, calls to the right; green added, red closed. Toggle ΔOI or ΔGEX, and Center on spot. Covers ±12% of spot (up to ±25%). Hover a strike for its multi-day build.
- 1-day build — a heatmap of each morning's net OI change over 5, 10 or 20 days, and newly listed expiries.
- ΔGEX = OI change × today's gamma — how much the positioning change shifts dealer exposure at today's prices.
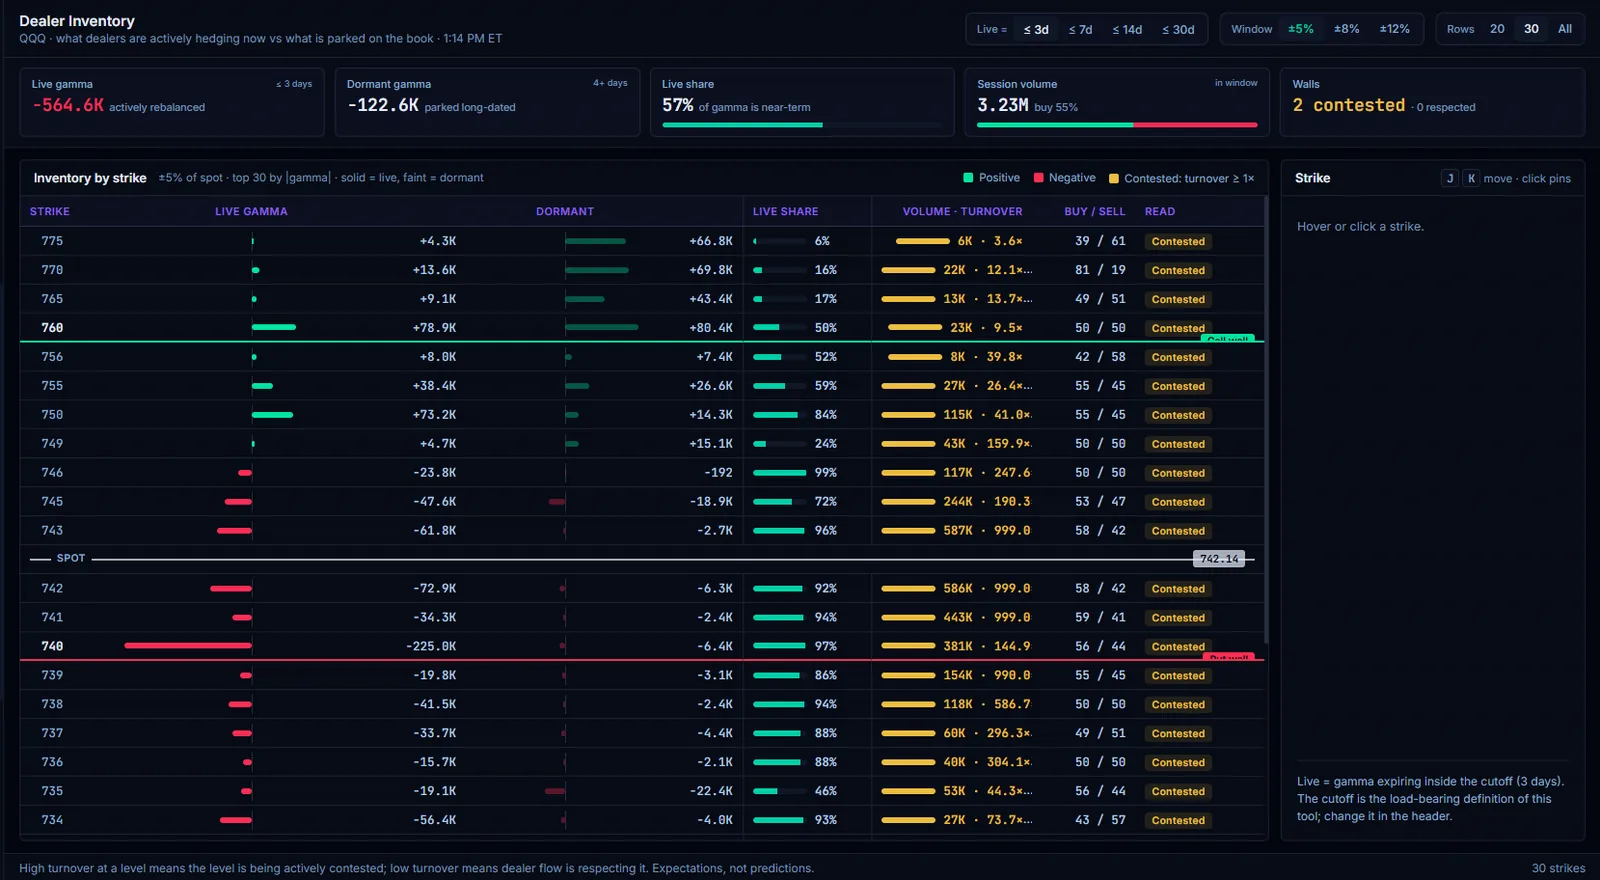
- Live gamma — gamma expiring inside the cutoff (Live = ≤ 3d, ≤ 7d, ≤ 14d or ≤ 30d), which dealers rebalance actively. Dormant gamma — longer-dated gamma that is parked. The cutoff is the key setting for this tool.
- Tiles — live gamma, dormant gamma, live share, session volume in the window (with buy share), and how many walls are contested vs respected.
- Inventory by strike — live gamma (solid) and dormant gamma (faint), live share, volume and turnover (today's volume ÷ open interest), buy / sell split, and a read.
- Contested — turnover of 1× or more: the level is being actively traded through. Respected — a wall or flip with turnover under 0.5×: dealer flow is leaving it alone.
- Controls: window ±5/8/12%, rows 20 / 30 / All. Hover a strike, or use J / K and click to pin one, for the detail panel.
What it shows
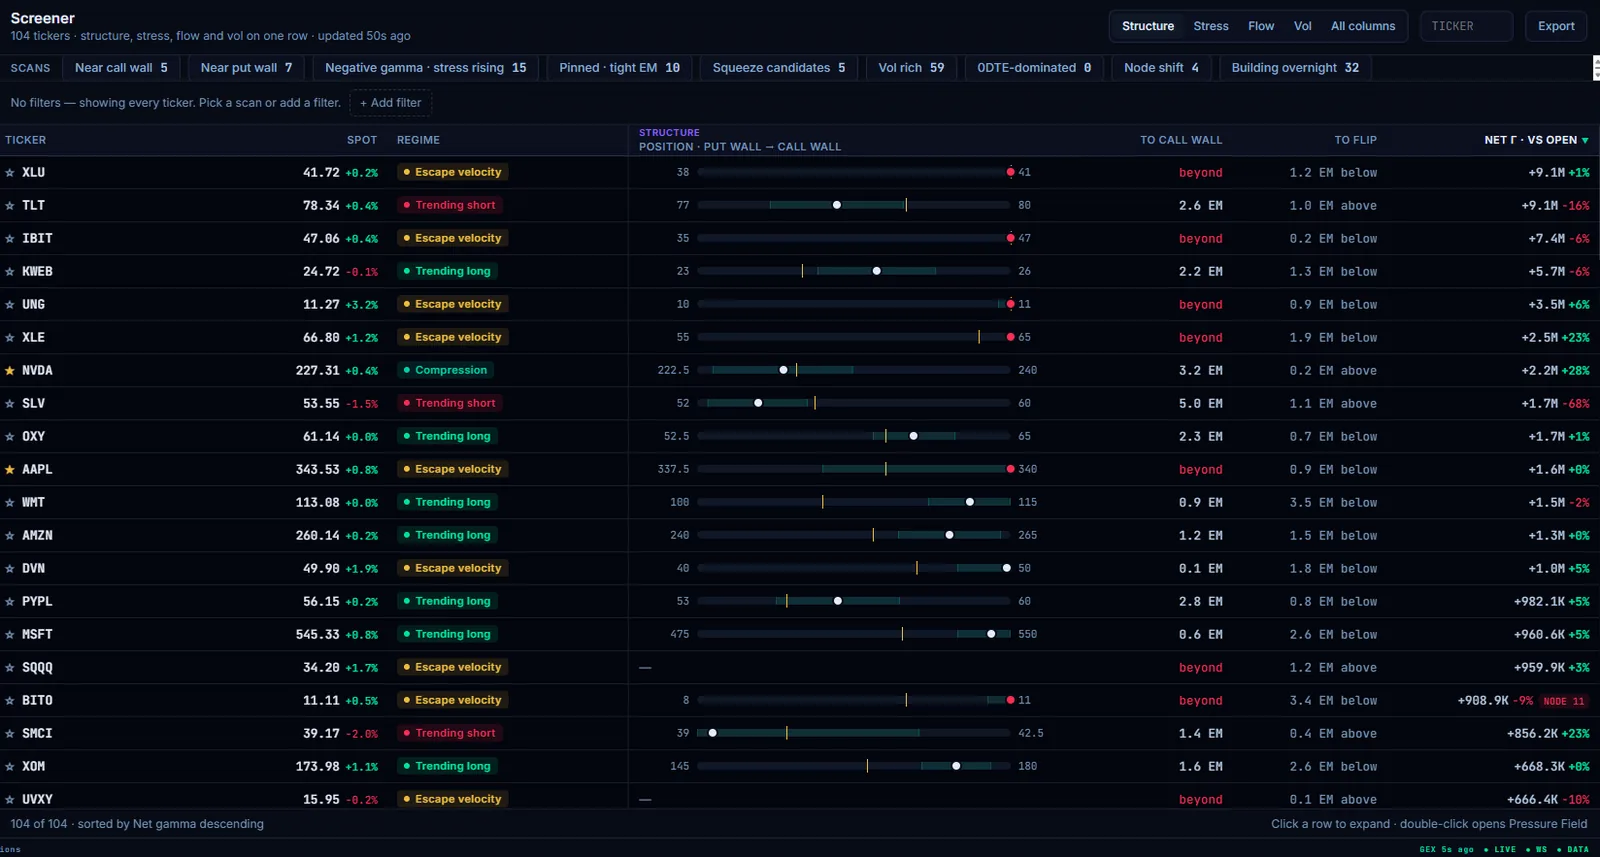
All 150+ universe tickers in one table. Column groups: Structure, Stress, Flow, Vol or All columns.
- Structure view — spot, regime, a position bar showing where spot sits between the put wall and call wall, distance to the call wall and to the flip (in expected moves, or "beyond"), and net gamma with its change vs open. A NODE badge marks a large node shift.
- Other groups add SSS, FPI trend, hedging velocity, net premium, OI Δ overnight, IV − RV, skew, and 0DTE share of gamma.
- Built-in scans with live match counts: Near call wall, Near put wall, Negative gamma · stress rising, Pinned · tight EM, Squeeze candidates, Vol rich, 0DTE-dominated, Node shift, Building overnight.
- + Add filter for custom filters, saved scans, ticker search and Export to CSV. Click a column to sort. Stars mark your watchlist.
- Click a row to expand it; double-click to open that ticker in the Pressure Field.
Setup
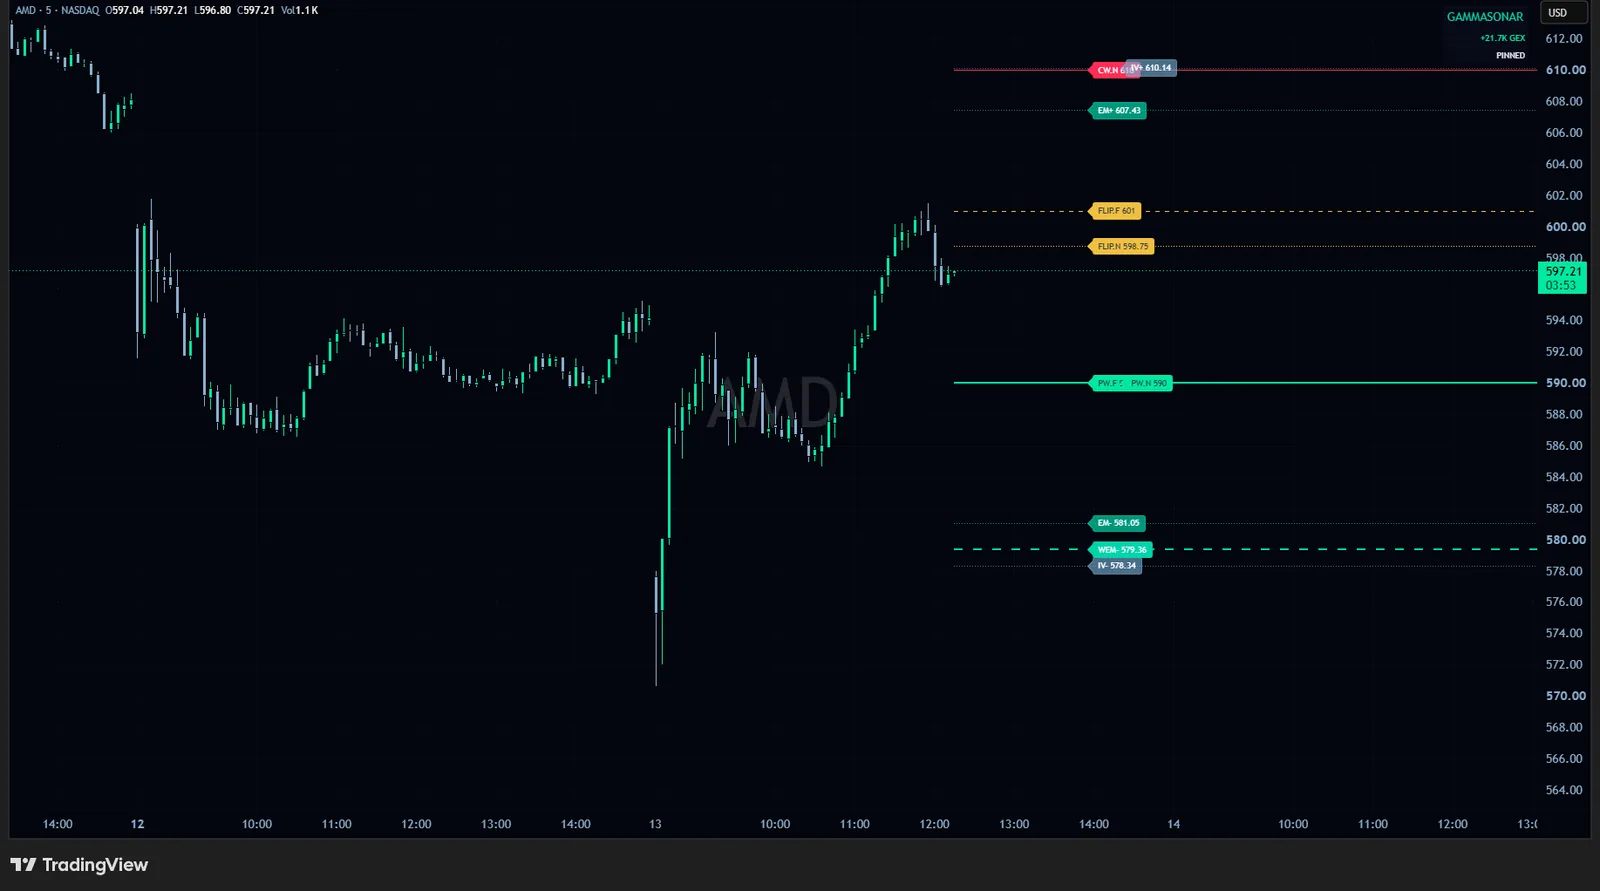
The indicator, GammaSonar GEX Levels, detects the chart's ticker automatically and draws the levels for any universe ticker. A small status box in the corner shows net GEX and the regime as of generation. When two levels land on the same price (for example PW.F and PW.N), their labels sit side by side on one line.
| Line | Meaning | Default |
|---|---|---|
| CW.F · PW.F · FLIP.F | Call wall, put wall and flip from the full chain (all expiries) | On |
| CW.N · PW.N · FLIP.N | The same levels from the closest expiry only | On |
| EM± | Straddle-priced daily expected move | On |
| WEM± | Weekly expected move (fixed Monday–Friday, from Friday's close) | On |
| IV± | Implied-volatility-based expected move | Off |
| VIX± | VIX-implied expected move (SPX, SPY and QQQ only; divisor 16 by default) | Off |
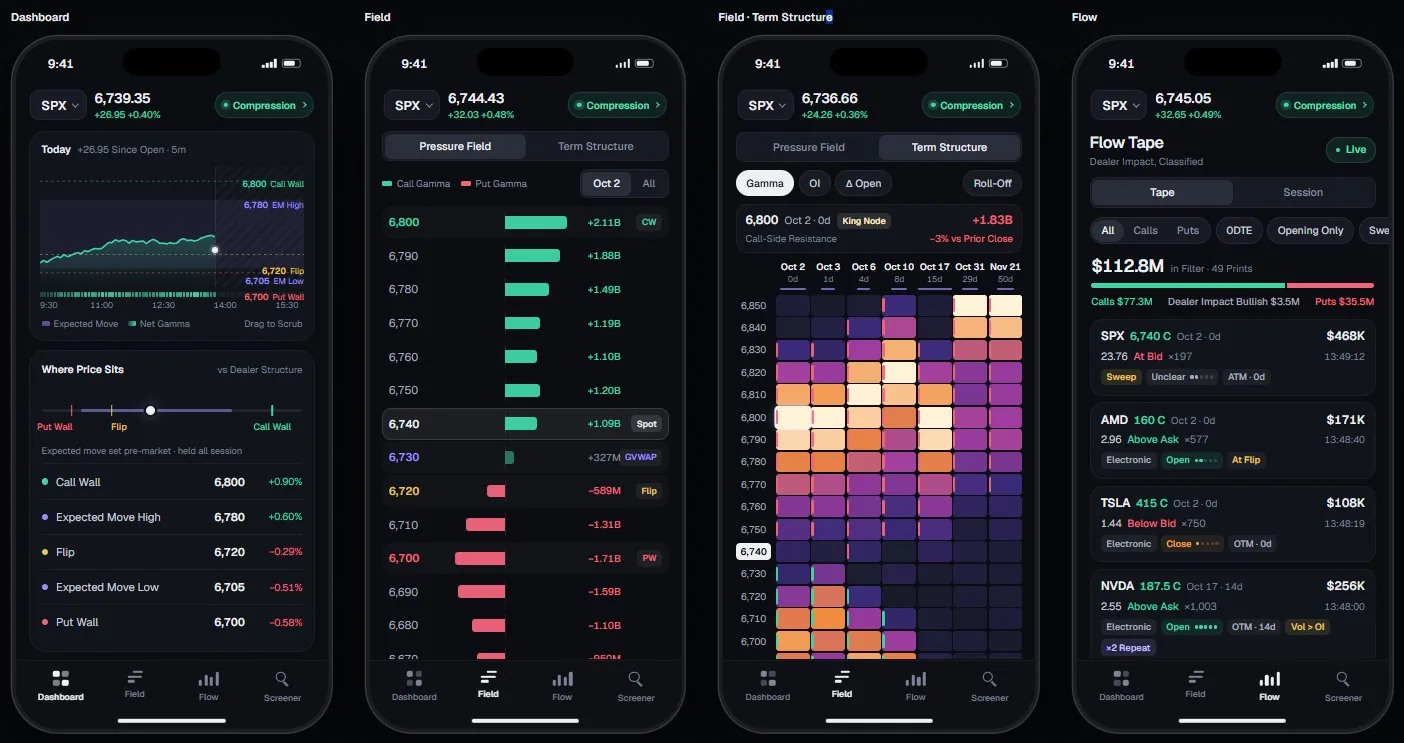
The mobile layout has a header with the ticker picker and a regime chip (tap it for the regime sheet), plus four tabs:
| Tab | What's in it |
|---|---|
| Dashboard | Today's chart with expected-move band, walls and flip; where price sits relative to key levels; the session Read; metric tiles; Structural Stress. |
| Field | Pressure Field (net gamma ladder, front expiry or all) and Term Structure heat map. |
| Flow | Flow Tape as cards, with the same filters and labels as desktop, plus a Session view. |
| Screener | Squeeze Candidates and Node Shift scans up front; the other scans under More Scans. |
Account and subscription settings are behind the avatar. For the full tool set, use a desktop browser.
Pre-market (from about 6:30 ET)
First hour (9:30–10:30)
Midday (10:30–1:30)
Afternoon and close (1:30–4:00)
By regime
| Regime | Playbook | Tools to lean on |
|---|---|---|
| Compression · Pinned | Range: fade edges, small targets | Pin Risk, Expected Move, Dealer Inventory |
| Trending long / short | Trade with the lean: buy pullbacks above the flip, sell rallies below it | Pressure Field, FPI, Vanna/Charm |
| Escape velocity | Watch whether the call wall rolls; follow if it does | Pressure Field vs open, Flow Street |
| Negative gamma · Cascade risk | Momentum over reversion, smaller size, wider stops | SSS, Flow Tape, Skew Dynamics |
You make better decisions when you know where your tools stop. Here are ours.
The positioning assumption
Model greeks
Greeks are model estimates (Black-Scholes), which assume things markets do not do — constant volatility, continuous hedging. They are a consistent estimate of exposure, not a measurement of it.
Open interest is overnight
OI arrives once a day, before the open, and reflects the prior session. Intraday changes in positioning are estimated from trades and calibrated each morning against the actual new OI file. Large early-session repositioning can make the morning base temporarily out of date. OI Overwatch shows what actually changed.
Inferred trade side
Buy/sell side, opening/closing and multi-leg grouping in the Flow Tape and Flow Street are inferred from where trades print and how they are reported. They are useful in aggregate and wrong on some individual prints.
Provisional thresholds
SSS bands, FPI bands and the Dealer Extrinsic ratio bands are provisional and will be recalibrated as history accumulates.
When to ignore the tools
- Major macro events — FOMC, CPI, unexpected geopolitical news. External flows can dwarf hedging flows.
- Earnings — single-stock structure built before the report may not describe what happens after it.
- Gaps and halts — greeks change discontinuously; levels can be skipped entirely.
- Thin sessions — holidays and half-days; fewer participants enforcing structure.
October 2026
- Command is the new landing page — candle charts with structural levels, a net gamma ladder with vs-open and vs-10-minute compare, session tiles, a plain-English Read and a cross-universe Watch panel. Read the Command guide →
- Flow Street (new) — intraday lanes showing where calls and puts are being bought to open. Read more →
- OI Overwatch (new) — confirmed overnight open-interest changes by contract and strike, with ΔGEX. Read more →
- Regime Classifier rebuilt around an explicit rule ladder with "what would change it" levels and a transitions log. Read more →
- Pressure Field — Stack view with every greek, expiry rail presets, overnight OI change highlights and the Obligation at strike panel. Read more →
- Charts upgraded across the platform with crosshair, last-value tags and double-click reset.
- Equity Screener — nine built-in scans, custom filters, saved scans and CSV export. Read more →
- Mobile redesigned: Dashboard, Field, Flow and Screener tabs. Read more →
- Universe expanded to 150+ tickers; watchlist holds up to 100.
- Status banners now announce data-vendor issues and maintenance directly in the app.
July 2026
- Flow Pressure Index rebuilt with full −1 to +1 range. Read the FPI guide →
- Adaptive OI calibration — intraday OI estimates retrain against the official OI file daily.
- SSS recalibration — thresholds remain provisional. Read the SSS guide →